<
article id=”post-951488″>
2026, it is learning how quickly an index provider can show Southeast Asia’s biggest economy the exit, wreaking havoc on its stock market.
The provider is MSCI, which may be about to follow through on its threat to downgrade Indonesian stocks to “frontier” status, or to something worse: a standalone market category.
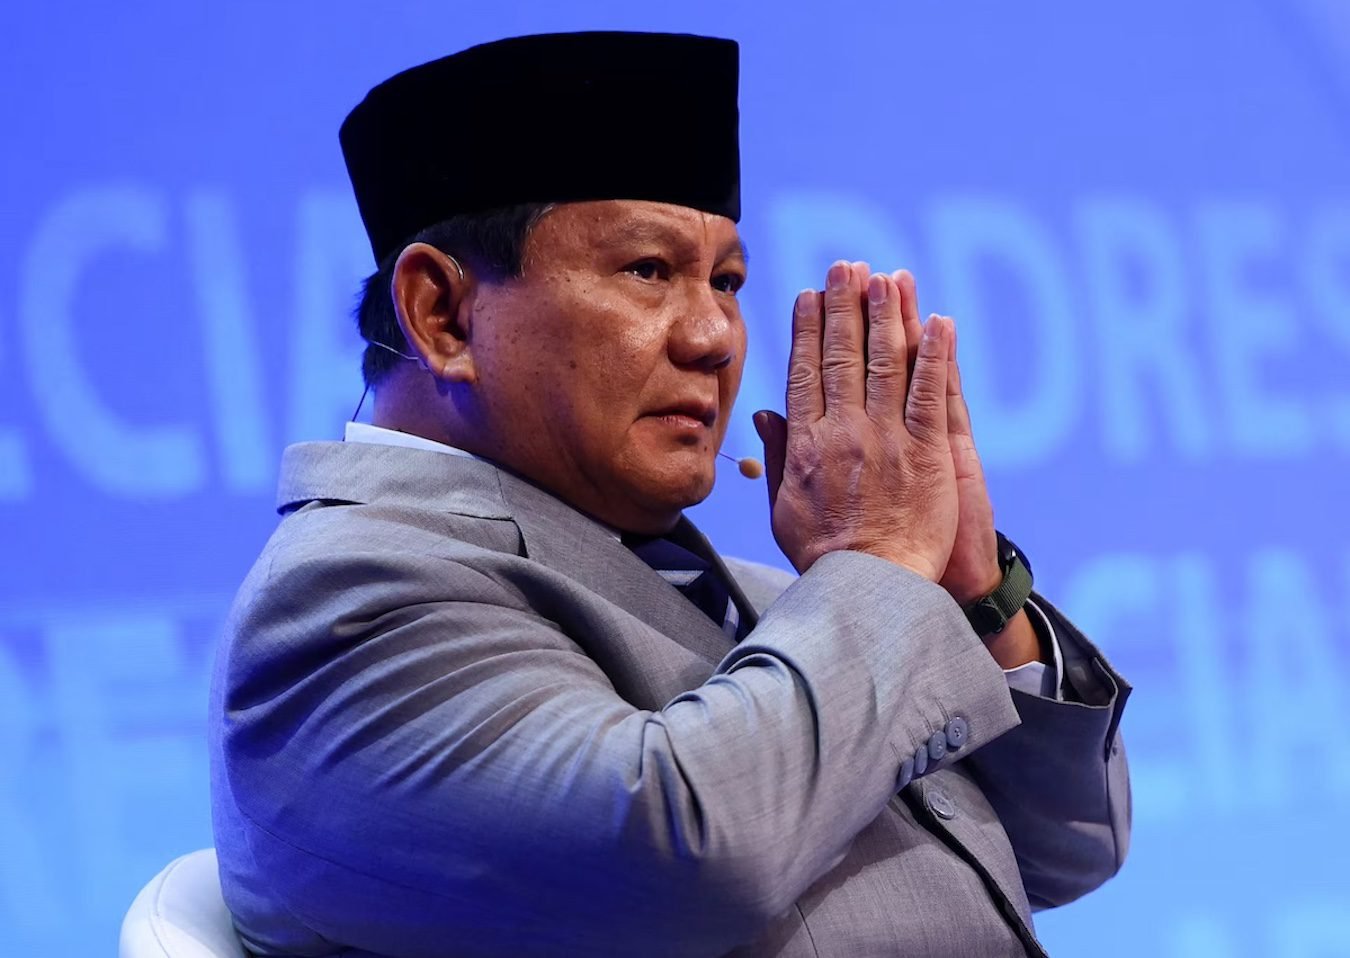
President Prabowo Subianto’s team moved quickly, meeting MSCI officials on Monday (October 19) to seek an eleventh-hour reprieve. But Team Prabowo should look in the mirror, because the ghosts of 1997 are back.
Twenty-nine years ago, a rupiah devaluation sent global capital fleeing as Indonesia’s economy collapsed amid the Asian financial crisis. President Suharto tried everything to stem the bleeding, including an ill-fated flirtation with a currency board.
By May 1998, with the economy in tatters, mass student protests forced Suharto from power. Successive governments have spent the years since rebuilding. Now the rupiah is setting new lows, and the bourse is suffering its steepest drop since the late 1990s.
However the MSCI standoff ends, investors can’t unsee what they have watched over Prabowo’s two years in office: rising economic nationalism, pressure on central bank independence, runaway populist spending, technocrats purged from the finance ministry, heavy state intervention and a giant new sovereign wealth fund with murky governance.
Now, “foreign capital is staging a full-blown exit from Indonesia’s equity market, and now the bond market is feeling the heat,” Eugenia Victorino, head of Asia strategy at Skandinaviska Enskilda Banken, told Bloomberg. “A sliding rupiah is eating real yields. Until the currency finds its footing, global money is content to watch this one safely from the sidelines.”
A former general and once Suharto’s son-in-law, Prabowo might at least project a veneer of transparency and market savvy. Instead, his economic team’s priorities seem to lie elsewhere. That’s been noted at the big three credit rating agencies, all of which have moved Indonesia’s sovereign outlook to negative, citing long-term fiscal strain.
To be sure, not all of this is Prabowo’s fault. The widening Iran war has exposed Indonesia’s continued dependence on imported fuel, despite oil reserves of its own that have been mismanaged over the years. But the rupiah’s slide, down 8.2% so far this year, the worst performance in Asia, reflects twin budget and current account deficits. Traders didn’t need MSCI to tell them that.
It doesn’t help that the chief executive of the Indonesia Stock Exchange, Jeffrey Hendrik, says the bourse was blindsided. “We never received any clue — nor any direct warning, either from MSCI or through any other parties,” he said of last Friday’s announcement.
Yet the rupiah’s slump was a clue. So was MSCI’s January warning that Indonesia was flirting with frontier status. Anyone surprised ten months later isn’t tracking the details as closely as foreign investors expect and a bourse leader should.
Last-minute horse-trading is no solution either. After meeting MSCI, exchange officials pledged to remove companies with concentrated ownership from the benchmark.
These account for roughly 18% of the Jakarta Composite Index by weight. The exchange also promised to disclose investors holding 1% or more of a company’s shares, and to identify which are affiliated with the company. But Hendrik then said implementation timelines would be detailed at a later date.
This is a trust-but-verify moment if ever there was one, and the damage is done either way. Gareth Leather of Capital Economics notes that MSCI had threatened frontier status but now argues even that would understate the severity of the problems.
Goldman Sachs says the burden of proof has shifted: avoiding reclassification will require clear evidence that the reforms have been consistently implemented and have materially improved market functioning.
The investment bank estimates that removal from MSCI could trigger US$5.6 billion in passive outflows, with active funds benchmarked to the indexes holding more than $8 billion.
All of this complicates Wednesday’s Bank Indonesia decision. Moody’s Analytics economist Stefan Angrick expects a 25-basis-point hike to 6% to defend the currency.
In late September, BI said it would scale back intervention amid concerns about reserves, so standing pat this week could send the rupiah to new record lows.
Investors sometimes get currencies wrong, but Indonesia’s case is a multi-year trend. The rupiah fell in every year from 2020 to 2025, often sharply. Less than 11 months into 2026, this year’s decline is already more than double 2025’s 3.5% loss.
The causes are no mystery. Last year’s budget deficit was 2.92% of GDP, just under the legal ceiling of 3%, which spooked bond investors and triggered outflows.
A record $8.5 billion trade deficit in mid-2025 added pressure as import demand outpaced commodity exports. BI also cut rates by 125 basis points last year, to 4.75%.
Since January, it has reversed course, raising the benchmark by 100 basis points to 5.75%. Inflation is tame at 3.28% in September, but with the Iran war dragging on, the subsidies keeping it that way are getting more expensive.
Few expected a former military strongman to be an economic reformer when he took office in October 2024. But the speed of the backsliding has still shocked many investors.
The first clear warning came in September 2025, when Prabowo abruptly fired Finance Minister Sri Mulyani Indrawati, long Indonesia’s face of economic credibility. She had served as finance minister from 2005 to 2010 under Susilo Bambang Yudhoyono, then as a World Bank managing director from 2010 to 2016, before returning in 2016 to anchor Joko Widodo’s reform agenda.
That agenda built on a long project. Since Suharto’s fall, Indonesian presidents have pledged to dismantle the sprawling kleptocracy he left behind. Widodo didn’t revolutionize the country, but he stabilized politics, pushed infrastructure and transparency reforms, cut extreme poverty in a nation of 288 million, and handled Covid better than many richer countries, the US included.
Markets increasingly saw Indonesia as a turnaround story, with BI Governor Perry Warjiyo, appointed in 2018, a key part of that confidence. Then, in July, Warjiyo abruptly left two years before his term ended. Investors were unconvinced by the “personal reasons” explanation, particularly after Prabowo named his nephew, Thomas Djiwandono, a deputy governor.
Prabowo’s pick to lead BI, Destry Damayanti, a Cornell-educated economist and senior deputy governor since 2019, was a relief, and markets hope she signals continuity. But it is early days, and she will be tested by Prabowo’s push for tighter executive control over an institution whose autonomy was hard-won.
All this plays out against Prabowo’s pledge to lift economic growth to 8% a year by 2029, a pace Indonesia hasn’t seen since the eve of the 1997 crisis. Second-quarter growth of 3.73% quarter-on-quarter is respectable but nowhere near that.
The danger is that Prabowo doubles down on fiscal stimulus, widening the twin deficits further and setting Indonesia on a collision course with markets, rating agencies and, by extension, MSCI. It creates a fact pattern on the ground in Jakarta that’s hard to ignore.
Prabowo’s push to meddle with BI’s mandate and roll out costly populist programs suggests a shaky grasp of the very forces that fueled the 1997–1998 crisis.
And despite the cautionary tale of the neighboring 1Malaysia Development Berhad state fund scandal, Jakarta has pressed ahead with a new sovereign wealth fund, Danantara — a move that has already raised red flags over governance risks and potential conflicts of interest.
Markets aren’t always right. But chaotic stock losses and rupiah volatility have investors sensing a 1997-like whiff in the Jakarta air. This puts the onus on Prabowo to show he has a more credible plan to take Indonesia forward.
Current fears of an accelerating backslide are the last thing the nation needs as it heads toward 2027. And moves to limit capital flows treat the symptoms, not the underlying problems.
In late April, when MSCI extended its review of Indonesia’s stock market, it seemed a wake-up call that most governments wouldn’t ignore. Ditto for back in January, when MSCI warned of “fundamental investability issues” in Indonesia’s stock market.
That statement was a stinging rebuke of Prabowo’s hyper-positive economic spin and triggered one of the most dramatic selloffs since the 1990s. Many investors now fear it’s too late to give Prabowo the benefit of the doubt.
Instead of strengthening Indonesia’s economic foundations and rebuilding market confidence, his finance ministry resorted to attacking economists in a style reminiscent of Donald Trump, further unsettling global funds.
Just as President Trump lashed out at Goldman Sachs’ chief economist for not toeing the US line, Prabowo’s team has publicly chastised Citibank analysts after a report warned that Indonesia’s budget deficit could widen.
Officialsdismissed Citi’s forecaster — who holds two master’s degrees — as “not a real economist.” But you don’t need a PhD to see that the world is taking Citi’s warning seriously, least of all MSCI.
Follow William Pesek on X at @WilliamPesek