Trump commercial railing against his enemies kept airing after court blocked it
Trump commercials paid for by the US government continued airing on TV the day after a judge blocked the ads because they likely violate a US law against government-funded publicity or propaganda.
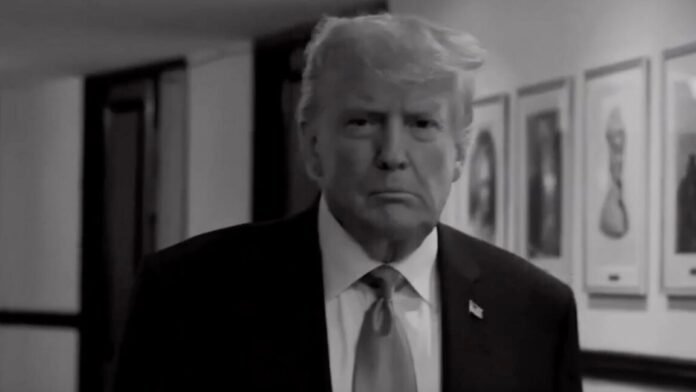
In the most widely aired commercial, Trump railed against his perceived enemies and said he would “liberate America from these villains once and for all.” The campaign also included a commercial praising Trump’s record as president, another in which Trump calls the US the “most exceptional nation ever to exist in human history,” and commercials related to the Iran war and the capture of Venezuelan President Nicolás Maduro.
US District Judge Jennifer Rochon issued a temporary restraining order (TRO) blocking the ads on Sunday, October 11, which took effect at 6:45 pm that night. The order said the government must cancel the ads, “including those placements for the evening of October 11, 2026.”
The Trump administration had told the court on October 10 that the Department of Homeland Security (DHS) advertising purchases were set to expire on October 11 and would not be renewed. Despite that, the ads continued airing the night of October 11 and on part of October 12. This was also a week after Trump’s October 5 statement that he would start paying for the ads “myself, and with money I raised for MAGA, Inc.”
A US attorney yesterday filed a status report saying that the government is now complying with the order and issued an apology. “As Your Honor is aware, the Court emailed the TRO to the parties yesterday at 6:46 p.m.,” US Attorney Jamie McDonald wrote in a filing. “Counsel for the Government emailed the TRO to agency counsel at 7:58 p.m. Agency counsel did not become aware of Government counsel’s email until this morning. The undersigned apologizes to the Court and the plaintiffs.”
The ads aired as part of a $20 million purchase order that US Customs and Border Protection (CBP) made on September 20 with LMD Agency, an ad firm. The DHS told the court that the ad placements through October 11 cost $19 million.
Trump admin said ads would stop Sunday
In the previous Trump administration filing opposing the motion for a temporary restraining order, one of the government’s arguments was that a court order was unnecessary because the ads would not run past October 11. It said:
DHS issued a purchase order to obtain media services from a vendor in support of U.S. Customs and Border Protection (CBP) for placing national media buys. The vendor has currently purchased media buys under the terms of the purchase order through tomorrow, October 11, 2026. DHS has directed the vendor not to make any additional media buys past October 11, and DHS has no plans to make any additional media buys under the purchase order or otherwise use appropriated funds on any similar contracts for the creation or distribution of the media that is the subject of this lawsuit. Accordingly, the alleged offending conduct will end tomorrow, and Plaintiffs therefore will suffer no harm, let alone irreparable harm, absent an injunction.
The Washington Post reported yesterday that the ads kept running after the restraining order took effect. Nonprofit advocacy group Common Cause and other groups that sued the government submitted a filing later in the day notifying the court of the government’s noncompliance.
The Trump ads continued airing on programs including 60 Minutes, ABC World News Tonight, and America’s Funniest Home Videos. They ran nearly 400 times after the restraining order took effect, including 32 times on Monday, according to AdImpact data cited in the plaintiffs’ court filing.
“Plaintiffs do not presently seek contempt sanctions,” the groups said. “But given that the ads have continued to run on October 12—the day after Defendants insisted the ad-buy was no longer effective—Plaintiffs request a status conference to determine Defendants’ compliance.”
Judge: Ads “are purely partisan”
After the government filed its status report, Rochon scheduled a hearing for Wednesday “to discuss this and next steps in this action.” The lawsuit is in US District Court for the Southern District of New York.
The plaintiffs are Common Cause; Robert Hunter, a Democratic candidate for a state legislature seat in Alabama; Service Employees International Union Local 32BJ; and Empire State 32BJ SEIU PAC. Defendants include DHS, the Office of Management and Budget (OMB), and the Executive Office of the President.
Rochon found that the plaintiffs are likely to succeed in their claim that the Trump administration violated the 2026 Consolidated Appropriations Act requirement that no funding may be used “for publicity or propaganda purposes within the United States not heretofore authorized by Congress.”
“Defendants do not contest that the at-issue advertisements are purely partisan and unconnected to DHS’s official functions,” Rochon wrote. “Thus, the Court finds that Moving Plaintiffs are likely to succeed in showing that the advertisements are impermissible ‘publicity or propaganda’ under Section 718 [of the Consolidated Appropriations Act].”
Trump recycled ad from 2024 campaign
One of the ads “is almost identical to one used during President Trump’s 2024 campaign, other than the fact that its funding disclaimer now identifies the United States government rather than his presidential campaign,” Rochon wrote. “It depicts President Trump walking down a hallway while delivering a series of statements about his political adversaries. Among other things, he promises to ‘demolish the deep state,’ ‘drive out the globalists,’ ‘cast out the communists, Marxists and fascists,’ ‘throw off the sick political class that hates our country,’ and ‘rout the fake news media.’ This advertisement provides no information about DHS’s official functions.”
As of October 8, the ad “had aired approximately 9,679 times, generating an estimated 972 million impressions at an estimated cost exceeding $9.09 million,” Rochon wrote. Another $6.3 million was estimated to have been spent on four other government-funded ads challenged in the lawsuit. That’s about $15.4 million as of October 8, and more was spent over the next few days.
Rochon found “a clear and substantial likelihood” that the Trump administration violated the Administrative Procedure Act “because Congress did not appropriate funds for DHS to spend on disseminating the challenged advertisements.” Rochon said a restraining order was necessary despite the DHS claim that it had “no plans” to continue running the ads.
“Defendants also have not provided reasonable assurances that OMB will not reapportion funds from another source to continue running similar advertisements,” she wrote.
The temporary restraining order is in place for only two weeks, but it can be converted into a preliminary injunction that would keep the ads off the air while litigation continues. Trump, the White House, OMB, and DHS face a similar lawsuit filed by the Democratic National Committee in the federal court in the District of Columbia. A hearing on a motion for a temporary restraining order in that case is scheduled for Thursday.
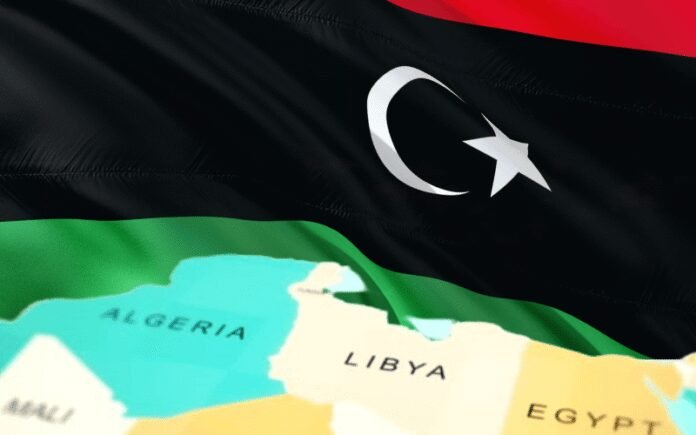
Libya’s eastern-based authorities have seized about 400 kg of hashish worth around 6 million dinars ($934,000) and arrested some suspects near the coastal city of Tobruk, officials said.
Libya has become a major drug transit route as gangs exploit the turmoil and conflict since 2011 when former ruler Muammar Gaddafi was toppled in a NATO-backed uprising.
The anti-drugs agency’s information and documentation officer, Ahmed al-Mismari, told Reuters that Saturday’s operation took place at a house in an agricultural area southeast of the city.
“The preliminary investigations revealed the shipment had been smuggled across the border with Egypt and was intended for local marketing and distribution within the Libyan market,” Mismari said.
The detainees, whose number was not confirmed, were from Libya and Egypt.
Pictures posted by the agency showed a large quantity of hashish wrapped in gold and black patterned packages marked with symbols including a horse and the year 2026.
Also on Saturday, a Libyan National Army brigade seized more than 1.3 million narcotic pills after a firefight with smugglers in the southeastern town of Kufra. Three soldiers were injured, according to an army statement.
As the war in Ukraine grinds into its fifth winter, the collapse of recent diplomatic initiatives and Washington’s explicit pivot from arming Kyiv to brokering a territorial freeze have laid bare a stark new reality.
In February 2022, Western leaders predicted that sanctions would cripple Russia within months and that a united West would see Ukraine through to victory. More than four years later, Russia’s economy has bent but not broken. The United States has turned from Ukraine’s chief backer into a reluctant broker. Europe is paying for a war it cannot win.
Ukraine’s fierce resistance has been central to this story. The country fought a brutal war of survival precisely because the liberal order failed to integrate it securely.
Through its ongoing resistance and rejection of imposed territorial surrender, Ukraine has forced the West to confront the limits of its own assumptions. It has shaped the contours of the emerging order even as it pays the highest price.
But Ukraine is also the place where a larger project came to grief. For three decades after the Cold War, the West assumed that free markets, democracy and Western-led alliances would advance together, each reinforcing the others. Ukraine is where all three assumptions failed at once.
The liberal moment
The project began as an economic doctrine. Ronald Reagan and Margaret Thatcher championed it in the 1980s: cut taxes, deregulate, privatize, open borders to trade and capital.
After the Soviet Union collapsed in 1991, open markets and liberal democracy came to be seen as two sides of the same coin, guarded by Western-led institutions such as NATO, the IMF, and the World Trade Organization.
Every American president from George H.W. Bush to Barack Obama pursued some version of it. Bill Clinton was its most effective champion. He signed NAFTA, helped launch the WTO and backed NATO’s first eastward expansion. In Europe, Thatcher’s legacy and a generation of Atlanticist leaders carried the agenda into the single market and the EU’s own enlargement to the east.
Francis Fukuyama gave the era its intellectual frame. His 1989 essay, expanded into the 1992 book The End of History and the Last Man, argued that liberal democracy had won the contest of ideas. The rest of the world, the reasoning went, would follow sooner or later.
The assumption was not merely that markets and democracy were desirable. It was that they were convergent: economic integration would produce political moderation, and Western-led institutions would manage the transition.
This was the convergence thesis. Ukraine is where it died.
NATO moves east
Victory bred confidence, and confidence bred expansion. A weakened Russia under Boris Yeltsin objected but could do little. NATO took in Poland, Hungary and the Czech Republic in 1999. The three Baltic states, Slovakia, Slovenia, Romania and Bulgaria followed in 2004, then Albania, Croatia, Montenegro and North Macedonia.
Warnings came from inside the Western establishment. In 1997, George Kennan, the architect of America’s Cold War containment policy, called expansion “the most fateful error of American policy in the entire post-Cold War era.” In 2007, Vladimir Putin used the Munich Security Conference to denounce it.
In early 2008, William Burns, then US ambassador in Moscow, cabled Washington that Ukrainian membership was the brightest of all red lines for Russia’s elite. Weeks later, NATO’s Bucharest summit declared that Ukraine and Georgia “will become members.”
Geography explains the alarm. Ukraine’s eastern tip lies east of Moscow, and its border is roughly 450 kilometers from the Russian capital. Napoleon in 1812 and Hitler in 1941 both came across the same open plains.
The West treated Russian objections as noise rather than as the predictable reaction of a great power with both a long memory — and an estimated 6,000 nuclear warheads. Yet NATO expansion, however provocative, did not dictate Moscow’s response. The West’s fatal error was assuming that economic integration would moderate Russian behavior.
Two miscalculations: Russia and China
The convergence thesis assumed that economic pressure would bring Russia to heel. It did not. Cut off from European markets, Moscow redirected its oil east.
India, which bought little Russian crude before 2022, became one of its biggest customers, and trade between Russia and China reached record levels. Russia’s economy suffered inflation and labor shortages, but it adapted and marshaled its considerable resources.
China was the second blind spot. Beijing has its own stake in Russia’s survival. A Russia broken into weaker states would, in Chinese eyes, open the way to a Western presence along China’s long northern border. Backing Moscow, short of open military aid, became a matter of strategic self-interest.
Behind both errors lay a deeper assumption: that the West would stay preeminent because of its economic weight and its political system. China’s rapid rise in manufacturing and technology undermined that belief.
The EU now runs a goods trade deficit with China approaching 1 billion euros a day, according to Eurostat trade data. Europe imports Chinese electric cars, solar panels and batteries while its own industries struggle to compete.
The global market that was supposed to spread Western values has instead strengthened a rival.
Not all factors are equal
It is tempting to treat these developments as a list of separate failures. They are better understood as a sequence in which each reinforced the next.
NATO expansion created the security crisis. China’s rise created the structural challenge that undermined Western preeminence. Trump’s election shattered the political consensus that had sustained the project.
These factors interacted. The convergence thesis assumed that each dimension of policy — security, economics, politics — would reinforce the others. In practice, they pulled apart.
Liberal internationalists never counted on Donald Trump, a president who treats free trade as a swindle and alliances as a protection racket. His second term made the break explicit.
Sweeping tariffs hit not only China but allies in Europe and Asia. He questioned NATO’s mutual defense commitment and pushed members to raise defense spending toward 5% of GDP.
Trump did not kill economic liberalism across the board. At home he cut corporate taxes and stripped away regulations, both core policies of the Reagan-Thatcher inheritance. Some scholars call his approach “nationalist neoliberalism”: walls on the outside, deregulated markets on the inside.
What Trump destroyed was the project’s international face — the idea that open trade and American-led alliances served everyone. For Ukraine, this was the part that mattered.
Europe is paying a high price for its ideological tunnel vision. The loss of cheap Russian gas raised energy prices and hit energy-intensive industry, above all in Germany.
Berlin has responded with increased defense outlays and infrastructure investment, but the political and fiscal strain is palpable. Plants that once symbolized the country’s export model are now being eyed for armaments production.
Many voters now see nationalist parties as the only way to remove the establishment that delivered these outcomes. Germany’s AfD came second in the 2025 federal election, and polling has shown Reform UK and France’s National Rally leading at various points in their respective countries.
Post-Cold War illusion
What died in Ukraine was not the entire liberal international order. It was the post-Cold War illusion that the order would expand seamlessly and without resistance. The core alliances remain, but they are no longer underpinned by the assumption of inevitable convergence.
In its place is a fraying, renegotiated multipolar world. The United States is turning inward, Russia is turning toward Asia and China has become a center of gravity in its own right. The old unipolar moment has ended. What replaces it is still unclear — but it will be shaped by powers that no longer assume their own values will prevail by default.
The confident chapter that opened with Reagan and Thatcher is closing. Its epitaph is being written in the ruined cities, displaced families and strained societies of Ukraine and the wider Europe that convinced itself that history had ended in its favor.
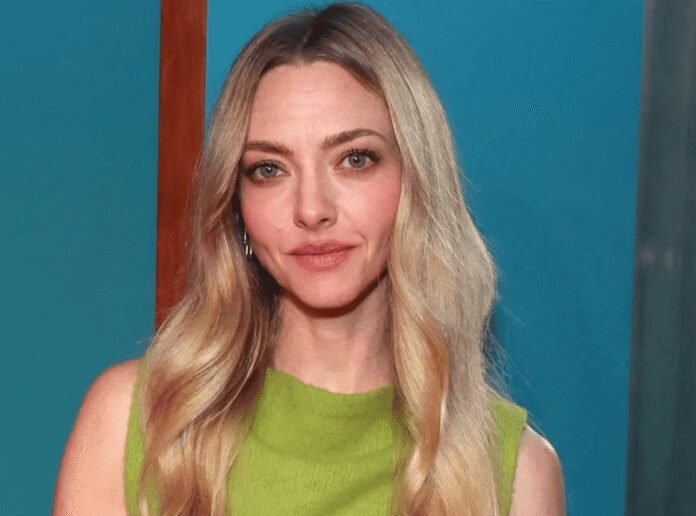
Hollywood actress Amanda Seyfried is drawing a firm line when it comes to her career, revealing that she recently turned down a television project because it required too many sex scenes.
The 40-year-old Oscar nominee, best known for Mean Girls, Mamma Mia! and The Housemaid, admitted that her feelings about filming intimate scenes have changed dramatically over the years.
And after spending more than two decades in Hollywood, she’s no longer willing to make herself uncomfortable just to land a role.
During a candid conversation with Alec Baldwin at the Hamptons International Film Festival on October 4, Seyfried explained that pretending to be romantically involved with another actor has become increasingly awkward.
“Our jobs are weird. And as I get older, it gets weirder,” she told Baldwin.
The actress acknowledged that performing romantic scenes with people she has no personal relationship with is simply part of the business, but she no longer approaches those moments with the enthusiasm she once had.
Earlier in her career, Seyfried said, kissing an attractive co-star while getting paid seemed like an exciting perk of being an actress.
Now, the situation feels very different.
Seyfried revealed that she recently passed on an unnamed television series because the role involved frequent sexual encounters.
“I don’t wanna do it. I’m uncomfortable with it. I’m not into it right now,” she explained.
She also said she has little interest in being physically exposed in front of unfamiliar co-stars, regardless of who they are.
The actress did not identify the television project she rejected or disclose how much money she may have been offered.
While her comments sounded decisive, Seyfried stopped short of declaring that she would never film another intimate scene.
She acknowledged that her feelings could change in the future, depending on the project and her personal circumstances.
For now, however, she is comfortable walking away from opportunities that don’t align with her boundaries.
Her decision also reflects how motherhood has changed her priorities.
Seyfried shares two children, daughter Nina, 9, and son Thomas, 6, with actor Thomas Sadoski.
The couple, who married in 2017, confirmed in September 2026 that they had been separated for some time, although they have continued focusing on raising their children.
During the festival discussion, Seyfried explained that her children are now old enough to notice her work, which has made her more thoughtful about the roles she accepts.
“I have kids now who are paying attention to what I do,” she said.
The actress also admitted that she was more willing to accommodate uncomfortable situations when she was younger, sometimes agreeing to things because she didn’t want to disappoint colleagues or jeopardize an opportunity.
Now, after years of success, she feels more confident saying no.
That confidence comes at a particularly successful point in her career.
Seyfried first captured widespread attention as Karen Smith in the 2004 comedy Mean Girls before becoming an international star in the 2008 musical Mamma Mia!.
She later took on more demanding roles, including her portrayal of adult film actress Linda Lovelace in the 2013 biographical drama Lovelace.
Her performance as Marion Davies in David Fincher’s Mank earned her an Academy Award nomination in 2021.
She also won an Emmy Award for portraying disgraced Theranos founder Elizabeth Holmes in the Hulu miniseries The Dropout.
More recently, Seyfried starred alongside Sydney Sweeney in the 2025 psychological thriller The Housemaid, which became a major international box-office success, earning more than $400 million worldwide.
Despite her lengthy career and numerous acclaimed performances, Seyfried told Baldwin that the movie’s success finally made her feel like a genuine Hollywood movie star.
Interestingly, her role in The Housemaid did not require her to perform sex scenes.
The actress has also continued pursuing challenging dramatic projects, including The Testament of Ann Lee and The Life and Deaths of Wilson Shedd, which was featured at this year’s Hamptons International Film Festival.
Her comments arrive as Hollywood continues examining how intimate scenes are handled on film and television sets.
In recent years, the industry has increasingly used intimacy coordinators to help performers establish boundaries and choreograph sensitive scenes safely and professionally.
But Seyfried’s remarks highlight another important distinction: Even with safeguards in place, an actor may simply decide that certain scenes are no longer something they want to perform.
And Seyfried is making clear that she doesn’t need a complicated explanation for that decision.
After years of accepting demanding roles and navigating Hollywood’s expectations, the actress is choosing projects on her own terms.
For now, that means turning down opportunities involving frequent sex scenes, even if they might otherwise be appealing.
And with an Oscar nomination, an Emmy Award and multiple box-office hits already behind her, Seyfried appears comfortable letting someone else take those roles.
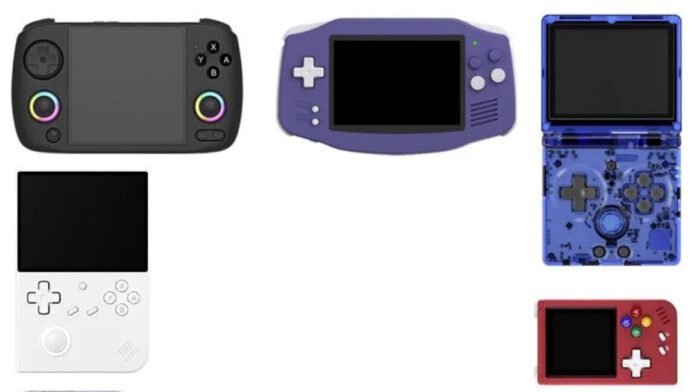
ESA targets Anbernic emulation handhelds as “superfake” piracy enablers
For years, Chinese hardware manufacturers have carved out a market niche with an array of handheld Android gaming devices focused on retro emulation and/or more modern game-streaming capabilities. Now, though, a major game industry trade group is targeting one of those manufacturers, Anbernic, asking the US Trade Representative (USTR) to add the company to its list of “Notorious Markets” that “engage in or facilitate substantial copyright piracy or trademark counterfeiting.”
TorrentFreak was among the first to notice the request from the Entertainment Software Association (ESA), which was submitted to the USTR last week. In it, the US trade group—which represents major publishers including Nintendo, Microsoft, PlayStation, Amazon, Epic, EA, Ubisoft, and more—notes that Anbernic devices “are routinely offered or shipped with removable memory cards preloaded with hundreds or thousands of unauthorized copies of copyright-protected video games published by ESA members.”
While many online sellers do include an SD card full of ROMs alongside emulation hardware of all types, Anbernic itself does not appear to do the same when selling directly from its website. Regardless, the ESA argues that these ROM-laden Anbernic devices selling through “normal retail channels” help to “normalize hardware-based piracy by delivering illicit catalogues through a polished consumer product.” This, the ESA says, meets the threshold for a “superfake,” an ill-defined designation that applies to “high-quality counterfeit trademark goods … on a commercial scale.”
Being included on the USTR’s Notorious Market List wouldn’t bring any additional direct legal consequences for a company like Anbernic. However, the USTR says the list “encourages the responsible authorities to step up efforts to combat piracy and counterfeiting” and notes that the list itself “increase[s] public awareness and help market operators and governments prioritize intellectual property enforcement efforts that protect American businesses and their workers.” Inclusion on the list could also presage a Section 301 investigation that could lead to legal consequences or restrictive import controls on the devices.
“Includes thousands of games!”
The ESA’s call-out of Anbernic to the USTR highlights the breakdown of a polite fiction that has long undergirded the distribution of emulators and emulation-focused hardware in the United States. In the not-too-distant past, software and hardware distributors that wanted to appear legitimate took pains to push perfectly legal emulators while completely disavowing any knowledge of the kind of copyrighted ROMs that could get them in legal hot water. If an end-user wanted to later find and load up those kinds of illegal ROMs on their own (instead of running legal homebrew games or backups of their own cartridges), well, that was nobody else’s business, was it.
These days, though, it’s trivial to find third-party sellers on Amazon, eBay resellers, annoying TikTok advertisers, or even reputable news sites boldly trumpeting and selling devices that include “thousands of games” from the past, ready to play from the moment you turn them on. To court customers who have never even heard of BitTorrent trackers or Warez sites, these sellers have brought illicit ROM distribution out of the Internet shadows and made it a core part of their business.
As major online retailers continue to ignore this blatant copyright infringement on their platforms, it’s no wonder the ESA has felt the need to act. But focusing on Anbernic, which just makes the hardware that powers these emulators, is an odd choice when these centralized e-commerce sites could do a much better job at preventing the wholesale advertising, sale, and distribution of illegal ROMs directly to consumers.
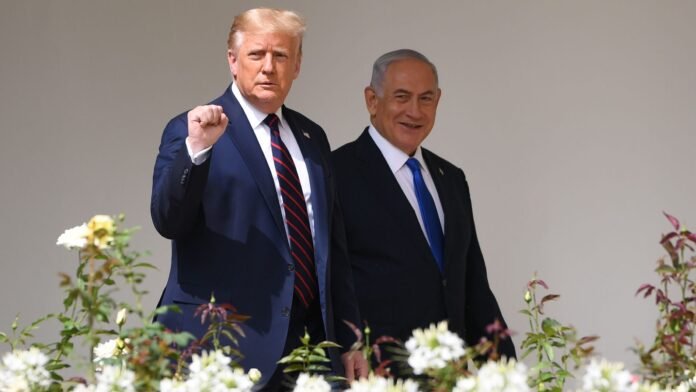
Netanyahu, President Trump Discuss Renewed Iran Strikes Ahead of Elections
President Donald Trump has not committed to a new military campaign against Iran despite discussions with Prime Minister Benjamin Netanyahu over possible joint US-Israeli strikes on Iranian military and nuclear sites, N12 reported Tuesday.
The possibility of renewed fighting has been raised several times in conversations between the two leaders over the past two weeks. According to US officials, Netanyahu appeared to favor resuming attacks before Israel holds elections on Oct. 27, pointing to concerns over renewed Iranian nuclear activity.
President Trump has publicly said he would not attack Iran before the US midterm elections, while a senior US official described his position on renewed military action as repeatedly shifting.
A senior Israeli official offered another account of the discussions. Netanyahu told Israeli security chiefs in recent days that President Trump was the one who raised a potential new campaign before the elections and asked whether Israel would participate.
“Bibi spoke with the president about it several times, and the president told him, ‘Well, you know what, Bibi, go ahead and get ready.’ But he didn’t really give him any commitment. ‘Go ahead and get ready’ could mean now, it could mean later, and it could mean never,” a U.S. official said.
President Trump appeared initially inclined to approve Netanyahu’s proposal before his interest diminished, according to a senior Israeli official.
Preparations are continuing despite the absence of a decision. The Israel Defense Forces and US Central Command (CENTCOM) are on high alert and are completing readiness measures in case President Trump changes his position, according to the sources.
Renewed fighting could affect both Israel’s Oct. 27 elections and the U.S. midterm elections on Nov. 3.
Defense Secretary Pete Hegseth and CENTCOM are the leading supporters in the US administration of another large-scale military operation against Iran, a second senior US official said. Most of President Trump’s advisers instead support maintaining economic pressure and sanctions.
“They argue that this economic strangulation is working better and better. Let’s keep doing it,” the second US official said.
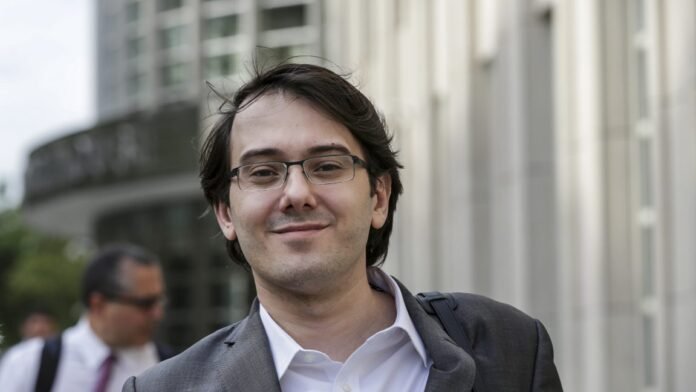
However, according to the Federal Trade Commission and the attorneys general of seven states, Shkreli has “flagrantly and repeatedly” violated that ban nearly the entire time—allegedly by trading stock in dozens of drug companies and discussing the industry during livestreams on social media.
On Tuesday, the FTC and the seven states asked a federal judge to hold Shkreli in contempt for the alleged violations. The states include New York, California, Illinois, North Carolina, Ohio, Pennsylvania, and Virginia—the same states that joined the FTC in suing Shkreli in 2020 over the “elaborate anticompetitive scheme” involving the anti-parasitic drug, Daraprim. The scheme raised the price from $17.50 per pill to $750 per pill virtually overnight, while blocking generic competitors from entering the market.
“Egregious” conduct
In 2022, the federal court recognized the “seriousness” of issuing such a lifetime industry ban, but ruled that “Shkreli’s egregious, deliberate, repetitive, long-running, and ultimately dangerous illegal conduct warrants imposition of an injunction of this scope.” The ban, among many things, “explicitly prohibits” Shkreli from owning stock in pharmaceutical companies and making public statements that could influence a pharmaceutical company’s business, according to the FTC and the states.
With the alleged violations, the FTC and the states are now seeking to force Shkreli to divest from all pharmaceutical companies and pay a fine equal to his profits from trading pharmaceutical company stocks. They also want the court to lay out “clear and escalating consequences” if Shkreli violates the ban in the future, including further financial penalties and incarceration.
“The extensive record compiled by FTC staff shows that Mr. Shkreli chose to blatantly disregard the order after leaving prison,” FTC Commissioner Mark Meador said in a statement. “Among other actions, he has traded pharmaceutical stocks and actively sought to influence the business and management of multiple pharmaceutical companies through public commentary, in violation of the terms of the injunction. … A lifetime industry ban is only effective if breaches are met with consequences commensurate with the seriousness of the order.”
In a response, Shkreli said he was surprised by the FTC’s filing. “I could see totalitarian NY AG Letitia James trying to limit a citizen’s free speech but not from Trump’s FTC,” he wrote on social media.
“Magic trick”
The brief filed by the FTC and the states breaks down Shkreli’s alleged violations in four phases:
(1) a 2022 trading competition with another YouTuber; (2) shorting a small biotech firm in 2024, along with trading in other Pharmaceutical Company stocks; (3) a 2025 trading challenge in which he shorted three small biotech firms along with trading in many other Pharmaceutical Company stocks; and (4) a trading challenge begun in June 2026 with a $10,000,000 account in which he is again trading in Pharmaceutical Company stocks.
In numerous livestreams on various social media platforms, Shkreli would sometimes show his accounts on screen, the filing said. He discussed pharmaceutical companies at length, evaluating stocks and predicting the outcomes of pivotal clinical trials. In 2025, he told his viewers about his “magic trick,” saying: “It doesn’t matter what trades I make because I can always find a couple of biotech stocks to smoke.” Later in the year, Shkreli advised his viewers to short one pharmaceutical company’s stock, and the company’s stock price quickly dropped 17 percent.
The FTC and the states wrote in their filing that the stocks Shkreli discussed in livestreams are “likely the tip of the iceberg.” FTC staff only reviewed a fraction of Shkreli’s social media activity, and Shkreli has made several references to other accounts he has.
“I have some other accounts that I’[d] show you, but, like, I know feds are watching, so f[*]ck that,” he said, according to the filing.
Rallye Sirocco, a nonprofit regularity rally with a humanitarian mission, will hold its first edition Dec. 18-23 in Morocco. The event is limited to 15 crews, or 30 participants, and will cover 1,035 kilometers (about 643 miles) from Marrakech to the edge of the Sahara.
Part of the participation fees will fund initiatives for 323 students in two Moroccan communities, organizers said.
A test of precision, not speed
In a regularity rally, crews must keep to set average speeds and reach checkpoints at scheduled times rather than race for outright speed. The inaugural edition will have four stages over six days. It is open to entrants without a motor racing competition license.
Organizers said the event rewards precision, consistency and teamwork in varied conditions.
The route
The rally starts in Marrakech and crosses the High Atlas mountains toward Ouarzazate, which organizers describe as the gateway to the desert. Crews then continue to M’Hamid El Ghizlane, at the edge of the Saharan dunes, before heading north through Zagora and the Drâa Valley, one of the world’s largest oases.
The route then passes through Foum El Oued and Taznakht, known for Berber crafts, and ends at the Ksar of Aït Ben Haddou, a UNESCO World Heritage Site.
What entrants receive
Each crew will receive an all-inclusive package that covers:
an official MG ZS Hybrid+ vehicle
fuel
accommodation
meals
cultural activities
official clothing
event logistics
Crew tracking and safety support will use Sirocco Tracker, built on Teltonika hardware. A companion tool, Sirocco Map, is also part of the event’s digital offering. Timing, regularity calculations and real-time standings run on a separate regularity system.
Support for students
The humanitarian initiatives target 323 students: 112 in M’Hamid El Ghizlane and 211 in Aït Ben Haddou. Organizers said they aim to promote responsible tourism, showcase the regions visited and pair a passion for motoring with concrete support for students in the two communities.
Organizers and partners
Two nonprofit associations are organizing the rally: ASACM and the Association de la Jeunesse Marocaine en France (AJMF). MG is the title partner. The Fédération Marocaine des Véhicules Anciens (Moroccan Federation of Vintage Vehicles) and the Association de la Jeunesse Marocaine à Toulouse (AJMT) support the event.
More information is available at rallyesirocco.com.
For most of the past thirty years, the semiconductor industry ran on a remarkably clean division of labor. Everybody knew their place.
The caricature was almost this simple: TSMC printed. Memory makers crammed capacitors. Designers drew. And the money followed the drawing.
TSMC took designs from Nvidia, Apple, AMD, Broadcom and others and reproduced them in silicon with a discipline nobody else could match. More importantly, it resolutely avoided becoming a product company competing with its own customers. That neutrality became one of its greatest assets. Companies that would reveal almost nothing to one another were willing to entrust TSMC with their most valuable intellectual property long before a product reached the market. TSMC’s prosperity depended on manufacturing their ideas, not replacing them with its own.
Memory occupied another well-defined lane. Samsung, SK hynix and Micron certainly designed extraordinarily sophisticated products, but economically they were treated largely as manufacturers: fit more bits into less silicon, improve yields, lower the cost per bit, and survive the next cycle. The products were relatively standardized. Pricing was brutal. Excess capacity could destroy profits almost overnight.
Much of the industry’s architectural power sat elsewhere. Nvidia, Broadcom, Apple and Qualcomm defined the architecture. TSMC manufactured it. Memory companies supplied a critical ingredient. The architects told the rest of the industry what to make and captured a disproportionate share of the value.
That arrangement is beginning to break. We’ve discussed the shifting power between designers and manufacturers in our notes before (here and here), but this note is about something different.
What is taking it apart is Samsung’s unusual shape and its sudden ability to pay for that shape.
Chip manufacturing has reached the point where the next gains require the old partitions to dissolve. Design and manufacturing. Logic and memory. Packaging and die-printing. What moves inside a package and what moves between packages. Power, heat and data movement are making those boundaries harder to preserve. A company that can optimize across several of them now holds something its competitors have to answer.
A few months ago, in Goliath’s World and the Encroachment Imperative, we wrote about giants eating the hardware middle class, moving into adjacent layers because complexity drew them in and because the specialists could no longer keep up. That was giants against everybody else. This is the sequel. The giants are still consuming the middle class. They have now started on each other.
It is also a sequel to Memory by Design, where we argued that memory and logic have begun to merge. The merging still looks elementary. Its consequences do not. Memory becoming architectural territory puts pressure on boundaries that TSMC and Nvidia once relied upon.
So the two layers that spent three decades taking what they were given, the foundries and the memory makers, are now pushing into the layer that used to tell them what to make. They can afford to. They are the richest companies in the industry. The layer being pushed has seen it coming and is pushing back downward. Nvidia is extending its design authority into the memory stack itself. SK hynix and TSMC have been deepening the kind of alliance neither of them needed while the old order held. Samsung, making both logic and memory, is the force they are arranging themselves against.
Much ink will be spent in the coming years on the shifting sands between the semiconductor and chip design giants. This mirrors what is already happening with the reduced monopolistic dominance of software and services giants today. An important aspect at present is how it all started with Samsung making more money than anyone ever in the history of human businesses and giving wings to its ambitions.
The company we said to own
Two years ago, we did something presumptuous: we wrote an open note to Warren Buffett suggesting that, if he ever wanted to own a semiconductor company, he should look at Samsung Electronics. We returned to the case a year later, asking whether Elon Musk’s manufacturing ambitions might lead him to consider a strategic stake in Samsung. The argument was never that Samsung was the best semiconductor company.
Samsung is not the world’s best foundry. TSMC is – by a margin that became painful enough, for Samsung, that we later devoted an entire piece to watching the two companies diverge over twenty years. TSMC won not merely the process race but the financial one: higher and steadier profits, better yields and eventually the valuation premium as well. Samsung has not lately been the best maker of high-bandwidth memory either. SK hynix took that crown.
Our case was about something else. Shape.
Samsung is the only semiconductor company of its scale with a leading-edge memory business, a leading-edge logic foundry, and advanced packaging capabilities within the same corporate structure. In the three-dimensional manufacturing era the industry is now entering, the control that shape makes possible is worth more than anyone has tried to put a number on.
This point is barely discussed anywhere, as far as we know, and the reason is, once again, in Samsung’s history. For much of the past twenty years, that shape looked less like an advantage than a tax.
The foundry consumed enormous capital while falling farther behind TSMC. Memory profits rose and fell with the cycle. Organizational silos meant that possessing several extraordinary capabilities did not automatically make Samsung extraordinary at combining them. Rather, given the paucity of resources, Samsung became a player far behind the cutting edge in the foundries, never seen as a threat because it just did not have sufficient capital to make an attempt. Samsung itself has been one of the best demonstrations of someone who had spread itself too thin.
What changed is the money. We have written about its scale twice: first when the profits arrived without precedent, then when we asked whether memory pricing had moved to a permanently higher plateau. The consequence is what matters here. The memory business now earns on a scale that lets Samsung fund all three legs at once, sustain the foundry through a prolonged development effort and pursue research whose commercial returns may lie beyond this decade.
The numbers are worth saying once. Samsung has committed around KRW110 trillion this year, roughly US$73 billion, to plant and research across the company: about $46-47 billion of capital expenditure and another $26-27 billion of R&D.
Samsung’s capex alone is larger than estimated mainland Chinese spending on semiconductor fab equipment this year. TSMC, however, has now raised its own 2026 capex guidance to an extraordinary $60-64 billion. Samsung’s rivals also have the resources to respond at extraordinary scale. The frontier itself has become a place where individual companies deploy capital on the scale of national semiconductor programs every year.
Samsung’s research budget still gives its peculiar corporate shape enormous new freedom. Group-wide R&D is running at roughly $27 billion this year, against about $8 billion at TSMC last year. In fact, TSMC’s total five-year spend on research is $30bn.
Samsung Electronics’ R&D spans businesses well beyond semiconductors, while TSMC’s is concentrated on semiconductor manufacturing. The totals therefore measure different scopes of research. The important point is that Samsung suddenly has more money than TSMC.
Memory profits now let Samsung fund memory, foundry, packaging, and speculative research at once. Samsung can now fund ambitions across memory, logic, and packaging on a scale that the company that has humiliated it for a decade cannot afford to ignore.
It is worth pausing on this comparison: For years, many have feared China’s semiconductor industry rise given its astronomical spending. Samsung’s annual capital expenditure alone now exceeds the estimate for mainland China’s semiconductor fab-equipment spending, although the measures cover different categories of investment.
This is the reason behind our title, the Frontier Express. Few have noticed how the resource-rich frontier has now begun to move forward. Even China’s catching up may be yesterday’s story.
Integration was always possible on paper. It has only just become affordable. The shape was a strength ahead of its time. The time has arrived. That is why Samsung’s competitors should be more worried today than they were before, when the organization chart looked identical.
The slab under the memory
High-bandwidth memory is built as a tower. Several layers of DRAM sit one above another. Underneath them sits a final piece of silicon called the base die. It is the foundation of the stack. It is the layer through which the memory communicates with the world outside.
For most of HBM’s life, that foundation was essentially plumbing. It moved signals, managed connections, and did the housekeeping required to make the memory above it work. Nobody thought of it as particularly valuable architectural territory. This was up until now.
The base die is moving onto increasingly advanced logic processes.
The same broad class of manufacturing technology is used to make processors. Its footprint is largely dictated by the memory stack sitting above it. The foundation has to sit underneath the building whether or not every square millimeter of that foundation is being put to sophisticated use. This creates a rather unusual situation. Beneath advanced HBM stacks, increasingly capable logic silicon is opening up new territory for whoever designs it.
Functions that once had to sit on the processor can begin migrating onto it. Decisions that once belonged entirely to the chip architect can begin being made inside the memory stack. The boundary between “the processor” and “the memory” starts becoming less obvious than the words suggest.
We explored the architectural possibilities in Memory by Design. Here, the question is: Who controls this increasingly valuable territory?
The EDA fabric hiding manufacturers’moats
It’s easy to misread what is happening. When a memory company or a foundry produces something clever, the instinct is to treat the cleverness itself as the advantage: Samsung has become better at design, perhaps TSMC has moved a little farther into system architecture, and therefore some value shifts toward manufacturing. But that explanation is too shallow. If the advantage were merely a better drawing, it would not last very long.
We have used the phrase “instant copyability” to describe the erosion of cognitive moats in a world suffused with generative AI. Once a design ships, competitors and their AIs can inspect it, understand it and reproduce much of what matters, increasingly quickly. A manufacturer therefore gains little durable advantage from becoming simply another clever designer. The real advantage lies in what an outside designer cannot inspect in a finished product: thousands of tiny manufacturing steps, tolerances, and process tricks that are hard to codify, yet collectively matter as much as a master painter’s brushstrokes.
For decades, the industry kept that knowledge on one side of the wall while letting thousands of customers design against it. A foundry did not give Nvidia or Apple a manual containing everything it had learned about making silicon. It translated the portion customers needed into process design kits, device models, design rules, standard cells, and verification decks. These were then embodied in the electronic design automation flows supplied by Synopsys, Cadence and others.
EDA became the membrane between manufacturing and design. The fab effectively said: keep these wires this far apart, make this connection no narrower than this, expect this transistor to behave within these parameters and we can manufacture what you draw. The designer did not need to know why a tolerance existed, how many failed experiments preceded it, or what the manufacturing line might already be capable of beyond it. Decades of process learning were distilled into a set of abstractions within which everybody could design.
That arrangement preserved the division of labor beautifully. Manufacturers could retain their deepest know-how while exposing enough of it for customers to innovate. Competing designers worked from broadly the same set of disclosed capabilities. But there was an important asymmetry buried inside the arrangement: the rulebook was never the manufacturing knowledge itself. It was only the part of that knowledge the manufacturer was ready to publish.
That distinction is becoming much more valuable.
New sequences of 3D manufacturing
Until now, design therefore sat downstream of manufacturing disclosure, by calendar as much as by construction. An architect could not confidently design around a capability that the foundry had not yet characterized, qualified and translated into a usable design environment. In a world dominated by two-dimensional chips, that delay was manageable. In the emerging world of three-dimensional semiconductor structures, it increasingly reaches into the architecture itself.
Consider a modern AI system bringing together logic, SRAM, HBM, and eventually optical I/O. The conventional assumption is that the architectural intelligence belongs primarily to companies such as Nvidia or AMD, while the manufacturers execute what those architects devise. But questions such as where heat should leave the structure, where power should enter, how far a vertical connection should travel, how two dies should be bonded, or where logic should sit relative to memory are no longer neatly divisible into “design” followed by “manufacturing.” Increasingly, the manufacturing choice and the architectural choice are the same choice.
More importantly, some of those choices must be made while the relevant manufacturing technology is still being developed. By the time a capability is sufficiently understood and repeatable to appear in a process design kit and become usable through standard EDA flows, the manufacturer may already have spent years learning what it can and cannot do.
The resulting asymmetry is not chiefly one of intelligence. It is one of information and time. A manufacturer can design against capabilities it knows are coming because it possesses the process data, defect history, thermal measurements and yield learning that indicate what may become feasible two or three generations ahead. An external designer sees the same capability later, once enough uncertainty has been removed for it to be exposed safely to customers.
That changes where architectural power can accumulate. Knowing today that a bonding process will reliably hold a certain tolerance in 2028 can justify a floorplan that an outsider cannot yet defend. Knowing where defects actually occur can determine where repair circuitry deserves its area. Knowing where heat concentrates can alter a structure before an external designer even knows that the hotspot exists.
None of those advantages can simply be copied from the finished product. The real asset is not the drawing. It is the accumulated measurement behind the drawing.
For decades, designers captured enormous value by drawing the best chip possible inside the rules manufacturers gave them. The emerging opportunity for manufacturers is to begin drawing before those rules have even been written.
Samsung moves first
Samsung has now begun to describe this opportunity in almost exactly those terms.
At its September keynote in Taipei, the company introduced CUBE, a framework for pushing three-dimensional structures across its memory business. Three of its four pillars are familiar enough:
Increase capacity by building upward.
Widen bandwidth by shortening the path between dies.
Reduce the energy required to move each bit.
The fourth is more consequential. Samsung calls it utilization, but the underlying question is architectural: Where should the logic sit, where should the memory sit, and which functions should move between them? Samsung’s claim is that owning both sides gives it more freedom to answer that question.
That is a subtle but important change in posture. Samsung is no longer presenting memory, foundry, and packaging simply as three businesses that happen to share a parent company. Increasingly, it is presenting them as ingredients that can be sold and developed together. The attraction to a customer is obvious. Instead of coordinating a memory supplier, a logic foundry and an advanced-packaging partner separately, a customer can potentially ask one organization to optimize the interfaces among all three.
The market is beginning to test the proposition. Broadcom has already engaged Samsung across memory, advanced logic, and packaging rather than through a single product category. Samsung is trying to deepen similar relationships with other large accelerator customers. AMD’s Lisa Su has visited Seoul twice in seven months. The company’s next-generation accelerators demand sharply more HBM. Korean reporting makes clear that Samsung wants the memory relationship to pull foundry and packaging work behind it.
That does not mean the bundle automatically wins. Samsung’s foundry still carries the scars of the past decade. Customers with access to TSMC have every reason to separate the attractive part of Samsung’s offering from the parts they trust less. The same AMD discussions reportedly illustrated that tension: Samsung had leverage through memory, yet the foundry work remained a much harder sell. Vertical integration is not the same thing as vertical competence. Owning memory, logic, and packaging under one roof only matters if Samsung can persuade customers that combining them improves the finished product more than mixing and matching best-of-breed suppliers would.
What matters at this stage is not whether Samsung can already displace TSMC or SK hynix in any particular account. It is that Samsung now has the financial resources, the technological breadth and, increasingly, the strategic intent to keep testing how far integration can be pushed.
If even part of that model works, the competitive question changes. The issue is no longer simply who makes the best memory, the best logic process or the best package in isolation. It is who can make those layers work together with the least friction and the greatest control. Just as the GPU stopped being merely a compute chip and became an architecture spanning memory, interconnect, networking and the rack, semiconductor manufacturing is beginning to stop being merely the act of printing a die and become the orchestration of logic, memory, packaging, power and thermals as one manufacturing system. Samsung is unusually placed to pioneer that transition.
Samsung also possesses one advantage that does not depend on winning every piece of business. It is the only major memory producer that does not have to invite another leading-edge foundry into the foundation of its most advanced memory products. As HBM base dies move onto more sophisticated logic processes, SK hynix and Micron increasingly need outside foundry partners. Samsung can keep that learning loop in-house.
Once one company can combine the layers internally, the others can no longer treat those layers as separate markets.
Everyone Answers
We should remember that none of the companies being encroached upon is short of money, technical depth, or ambition. These companies read technological tea leaves years before financial markets, which remain remarkably capable of staring at next quarter’s memory prices while missing what the resulting cash is about to finance.
SK hynix is the clearest example. Remarkably little serious work has been done on what it might build with a windfall that could take operating profit toward $200 billion this year. We get the headline capex number, roughly $35 billion, but mostly as a measure of how much capacity is being added rather than as a clue to the moats that may be getting built alongside it.
Samsung and SK hynix together are expected to finish the year with roughly $263 billion of net cash, more than twice Nvidia’s. They are beginning to deploy resources on a scale that only a handful of companies in history have possessed. This is not merely to make more memory, but to build capabilities unavailable to competitors without comparable money, process knowledge, and time.
TSMC’s resource pool is hardly standing still. At $60-64 billion, its capital expenditure this year will actually exceed Samsung’s. Almost all of it is concentrated on the manufacturing problem in which TSMC already leads. Its answer to Samsung’s breadth can therefore be greater depth: better logic processes, more advanced packaging, more capacity and a neutral integration platform through which many different memory and processor companies can meet. Samsung has the attraction of one roof; TSMC has the accumulated learning of being the roof under which much of the industry already operates.
It also begins this contest with something Samsung cannot buy overnight: a formidable lead in cutting-edge logic manufacturing, packaging execution and customer trust.
So Samsung’s breadth does not leave its competitors cornered. It changes the problem they have to solve. Samsung can integrate through ownership. The obvious answer is integration by contract.
SK hynix has moved closest to that model with TSMC. TSMC supplies the logic base die for its next generations of HBM. Memory design, logic process and advanced packaging are increasingly developed together rather than sequentially. What once looked like a straightforward relationship between a component supplier and a foundry is beginning to resemble a jointly assembled manufacturing platform. Micron is moving in the same direction for customized memory, though its ecosystem is less developed.
That is a much bigger change than the words “foundry partnership” suggest. A memory company is now inviting an outside logic manufacturer into one of the most consequential pieces of its highest-value product. The foundry is learning how that memory will be built, packaged, and connected years before it reaches the market. Samsung can keep much of that learning inside the company. SK hynix has chosen to recreate it across company boundaries.
TSMC, meanwhile, is becoming something rather different from the foundry of twenty years ago. It still does not need to design the customer’s accelerator. Maintaining that neutrality remains central to its model. But around the die it now orchestrates an expanding set of technologies: advanced logic, base dies, 2.5D packaging, 3D stacking, wafer-level integration and increasingly the electrical and optical connections between them. The more difficult it becomes to separate those pieces, the more valuable the company that defines the manufacturing environment in which they must all work together.
The partnership’s public scope is clear; its detailed division of intellectual property, economics and decision-making is not. Its effectiveness will depend on how well the companies coordinate across that boundary.
Neither model is obviously superior. Samsung avoids some coordination costs but carries weaker businesses and internal silos. The TSMC-SK hynix model combines companies that are individually stronger in their respective domains, but every important optimization must cross an organizational boundary.
And there is still a third elephant in the room. The companies doing this integration are suppliers to the firms that historically decided what the system should look like.
Nvidia takes the pen
The largest customer in this ecosystem has been watching the same boundaries move from the other side. For Nvidia, the danger is not that Samsung or SK hynix suddenly becomes better at drawing logic. It is that memory stops being interchangeable. Once a supplier owns an increasingly important piece of architecture inside the memory stack, switching suppliers becomes harder. Qualification takes longer. The component Nvidia can least afford to lose begins to acquire bargaining power over the entire accelerator. Apple’s plight in recent weeks shows why Nvidia would be reluctant to let memory makers and TSMC encroach unhindered.
Its answer is unusually revealing. In August, Nvidia introduced NVHBM, in which the memory controller moves off the accelerator and into the HBM base die. But instead of allowing the memory manufacturer to own that architectural layer, Nvidia designs the custom base die and controller itself. It has the memory companies validate and manufacture it. NVIDIA says the arrangement can deliver up to 30% more bandwidth, 15% lower HBM power and materially more usable compute area on the XPU. The engineering gains matter, but the strategic decision matters more: Nvidia has reached into the memory stack and taken authorship of the part that was becoming interesting.
There is another clue in the way Nvidia is commercializing it. NVHBM is intended to be available from multiple memory suppliers, not a bespoke technology tied to one manufacturer. That preserves something Nvidia has always valued enormously: substitutability. If Samsung, SK hynix and Micron can all build memory around an Nvidia-defined base die and controller, innovation can move deeper into the stack without handing any one memory vendor control of the interface.
Nvidia is also taking the idea beyond its own GPUs. NVHBM sits inside NVLink Fusion, the platform through which hyperscalers can connect their own custom accelerators to Nvidia’s interconnect and rack architecture. Amazon’s Annapurna Labs is the first announced collaborator. The company that once sold a GPU is therefore increasingly specifying how somebody else’s accelerator talks to memory, how it joins the scale-up fabric, and how the resulting machine fits into the rack.
This is encroachment running in the opposite direction. Nvidia has no reason to build a memory fab, just as it has no reason to build a leading-edge logic fab. Its defense is to move the boundary of what it designs farther downward, leaving manufacturing to others while keeping control over the interfaces through which their products connect to its architecture.
What is striking is how closely the engineering directions are beginning to converge. The controller is migrating toward the memory. Interfaces are becoming more customized. Logic and memory are being designed more intimately together. The disagreement is no longer primarily over what should happen. It is over who gets to draw it.
The circle tightens
These moves are beginning to reinforce one another. Samsung’s ability to combine memory, logic and packaging raises the value of integration. SK hynix cannot reproduce that structure internally, so it binds itself more tightly to TSMC. TSMC consequently moves deeper into the most valuable part of the memory system. Nvidia then sees memory gaining too much of its own architecture and pushes its specification down into the base die. Each company’s defense therefore shifts another boundary that the next company can no longer ignore. And this is before we see responses emerging from other giants in chip design.
There is no obvious resting point. If Nvidia succeeds in making several memory companies manufacture to one Nvidia-defined architecture, it will create pressure on other chip designers to get involved in their own HBM. Memory-makers will not mind such customization drives, even if the value of their own designed memory does not increase as much in the face of more design-led competition. All of this is hypothetical for now. The main point is about the loops of innovation we discussed in an earlier note.
The people between the giants
Our encroachment imperative note was about what happens to specialists when giants move sideways. This time, the pressure comes from several directions at once. Businesses whose value rested chiefly on an interface being standard and independently supplied look particularly exposed: memory-controller IP, generic die-to-die blocks, some package-design functions, and eventually parts of the design-service layer. If the interface becomes important enough for Nvidia, Samsung, a memory producer, or a foundry to own directly, there is less room for somebody whose business consists of sitting between them.
The outcome will be less tidy for packaging and testing. The leading foundries have pulled advanced packaging inward. Demand has repeatedly outrun their capacity and pushed work back towards outsourced semiconductor assembly and test (OSAT). Complexity can therefore destroy one specialist while making another indispensable.
Even the EDA companies are moving away from their old role as neutral translators of foundry rules. They are participating much earlier in customer-specific optimization. The common thread is that being an intermediary is becoming less valuable. Owning scarce knowledge, capacity, or qualification remains extremely valuable.
Terafab and the moving frontier
There is one important attempt to run the argument in reverse. If manufacturing companies can move toward architecture, why shouldn’t a sufficiently rich architect build its way into manufacturing?
Terafab is the cleanest experiment yet. SpaceX and Tesla describe a closed-loop facility combining advanced logic, memory, packaging and testing. Mask design and fabrication are brought much closer to the workloads that ultimately consume the chips. The first Grimes County phase commits more than $16.8 billion. The proposed complex will eventually exceed 100 million square feet. SpaceX’s own prospectus describes the objective explicitly: design, fabrication and deployment brought together so that each manufacturing cycle can feed the next design cycle more quickly. The ambition is enormous. The amount committed so far is not.
The headline Terafab numbers sound enormous until you put them beside the frontier it hopes to join. Its $16.8 billion first phase amounts to roughly one quarter of TSMC’s capital expenditure in a single year. Samsung will spend more than four times that amount on plant and research this year, while SK hynix is itself heading towards roughly twice that sum in annual capex. These incumbents will repeat much of that spending next year while learning from the factories already running.
That is the difficulty with entering this race late. Terafab does not have to catch TSMC, Samsung, or SK hynix as they are today. If meaningful production begins several years from now, it has to catch companies that will meanwhile have invested another hundred billion dollars or more, qualified several additional process generations, accumulated billions of additional manufacturing measurements and begun optimizing technologies that are still roadmaps today. The target is moving while the pursuer builds its starting line. Terafab need not match every incumbent capability to produce useful chips for its own customers. Matching their leading-edge economics, yields and breadth is the harder ambition.
Of course, semiconductor manufacturing does not yield its frontier merely to capital. Japan has supplied a useful contemporary experiment. Rapidus was created in 2022. It has around $15 billion of government backing, access to IBM technology and an ecosystem assembled specifically to restore Japan to the leading edge. Four years later, it has demonstrated serious technical progress and still targets mass production only in fiscal 2027, with commercial customers remaining the central unresolved question. Nobody regards that timetable as unusually slow; by semiconductor standards, it is extraordinarily fast.
Intel offers an even harsher lesson. It began with decades of leading-edge manufacturing knowledge, existing fabs, equipment relationships and thousands of experienced engineers. Yet recovering a lost process lead has consumed years and enormous amounts of capital. GlobalFoundries eventually decided the economics of remaining at the frontier no longer justified continuing its 7nm program at all. The difficulty is therefore not unique to new entrants. Once manufacturing leadership is lost, money shortens the journey only so far.
Terafab itself has already acknowledged part of that reality. Intel joined the project in April. Tesla intends to use Intel’s 14A manufacturing process rather than invent a leading-edge process from scratch. Last week, reports of possible TSMC involvement prompted Musk to clarify that Tesla and SpaceX intend to build and operate Terafab themselves. TSMC could potentially lease part of the site. The project remains genuinely vertically ambitious, but its first steps already draw upon manufacturing knowledge accumulated elsewhere.
That is precisely the point. Tools can be bought. Engineers can be recruited. Process technology can be licensed. What cannot be installed with the equipment is the history behind the equipment: years of defect maps, process-window adjustments, tool matching, contamination failures, thermal measurements, yield excursions, packaging mistakes and customer qualifications. Manufacturing leadership is partly a stock of machinery and largely a stock of accumulated learning.
Announcements are the easy part
None of this guarantees that the increasingly integrated structures described in this note will work. Three-dimensional integration compounds yield problems rather than abolishing them. Bonding tolerances narrow. Heat becomes harder to remove. Power delivery becomes more difficult. Package warpage and signal integrity become system problems. Qualification still has to be repeated customer by customer. An elegant roadmap structure may be impossible to manufacture economically at the required volume.
Even good ideas arrive with a bill. Moving a chip’s power supply to the back of the wafer is the headline feature of the next logic generation. It genuinely improves efficiency. It requires thinning the silicon so far that heat can no longer spread sideways. Simulation work shows the resulting hotspots are meaningfully hotter than the arrangement they replace. The change also lets designers pack circuits more tightly, which raises the power density that caused the problem.
Samsung does not have to win every contest for its ambitions to change the industry. It now has the money to pursue memory, logic, and packaging together. It can sustain expensive experiments and keep pressing where those businesses meet. Its rivals must make their own investment and architectural decisions while that challenge develops. Waiting for Samsung to prove every part of the proposition would mean waiting too long.
TSMC’s deeper integration platform, SK hynix’s network of foundry alliances, and Nvidia’s move into the HBM base die each has its engineering logic. Samsung’s expanding ambitions add competitive urgency to all three. Their responses, in turn, raise the demands on Samsung. The result is a frontier advancing through the interaction of exceptionally well-funded competitors, making the task harder for anyone still trying to reach it.
Markets can count the capacity that today’s profits will finance. The more consequential question is what those profits allow Samsung to attempt and what those attempts force others to do. The years ahead will contain fascinating developments in semiconductor technology, spurred ironically by memorymakers and foundries rather than the designers.
Nilesh Jasani is the founder and CEO of GenInnov Pte Ltd Singapore. Vibhu Sharma is a veteran of the semiconductor industry and a strategic technology advisor for GenInnov.
Originally published by GenInnov, this article is republished with permission.Read more at www.geninnov.ai/blog.
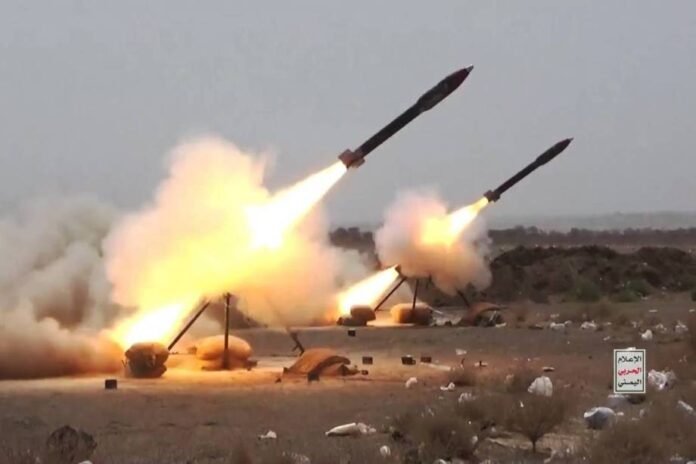
In this handout photo provided by the Houthi media center, fighters participate in a military exercise on March 12, 2024, in Sana’a, Yemen. [Photo by Houthi Movement via Getty Images]
The Saudi-led coalition said on Tuesday that it intercepted and destroyed two ballistic missiles launched by the Houthi group toward Dhahran and Haradh in eastern Saudi Arabia, Anadolu reports.
Coalition spokesman Turki al-Maliki announced in separate posts on the US social media company X that forces intercepted onw missile heading toward Haradh and another toward Dhahran.
The coalition said debris from the interception had fallen in a residential area in Dhahran and authorities are responding to the site.
It did not provide details on casualties or damage.
Saudi Arabia’s Civil Defense issued a warning earlier Tuesday of “potential danger” in the Eastern Province before announcing minutes later that the danger had passed.