<
article id=”post-952312″>
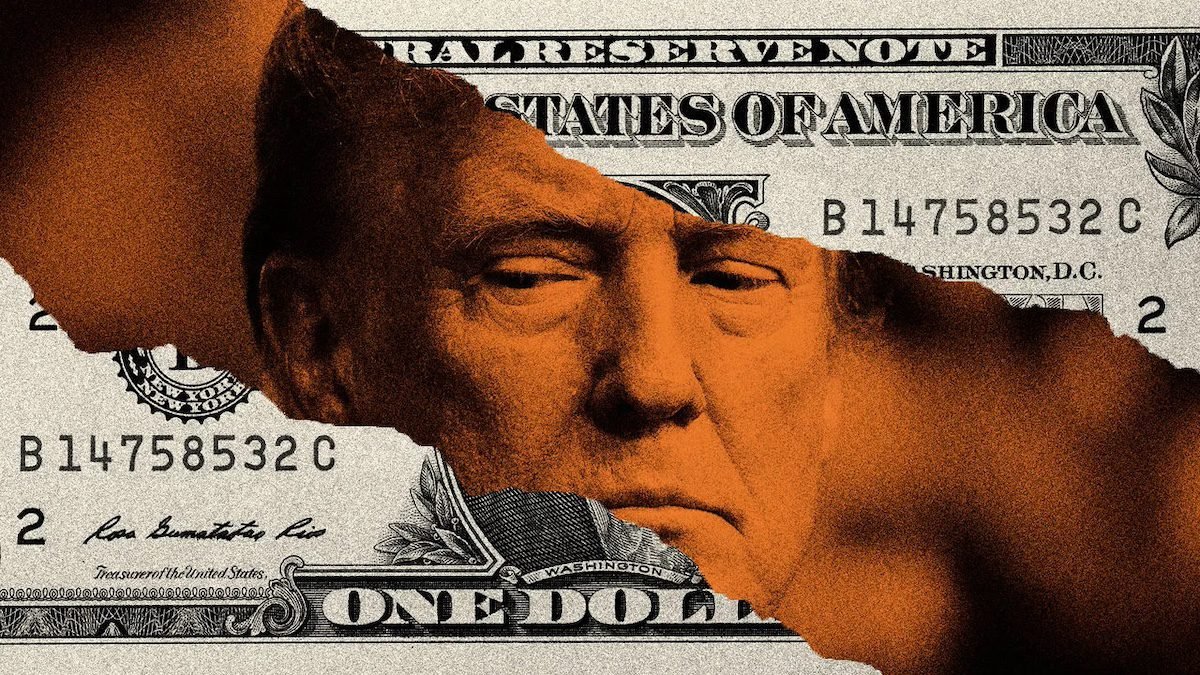
TOKYO – The dollar’s latest surge says as much about the rest of the world as it does about the US economy. At a 17-month high, the US currency is drawing global money chasing higher yields and the AI-driven growth story.
That may give it the momentum to power through the uncertainty around the midterm elections, including any efforts by the Trump White House to interfere with the results. The Democrats won big on Tuesday, scoring both House of Representative and Senate majorities.
The true scale of Democratic victory won’t be known for days, but Trump’s party was widely routed, with margins wide enough across the nation that Trump at least initially seemed to accept the historic defeat in press interviews.
Markets gyrated on the prospect of Democratic policy pivots on fiscal policy, AI, the Iran war and investigations into the Trump White House. Stocks in general seem poised to rise while the dollar dipped slightly against the yen, pound and euro.
When the political dust settles, though, markets seem to expect yet another gravity-defying year for the dollar.
MUFG Bank says the Democratic sweep would “likely be modestly positive for Asian FX,” because fiscal gridlock would curb expectations of further US spending, weighing on yields and the dollar.
Manulife’s Nathan Thooft agrees that divided government means fewer changes and “a degree of stability,” but cautions against overstating the long-term impact, since currencies follow relative growth, inflation, rates and capital flows more than elections.
Trump will still have significant levers, though. J.P. Morgan Asset Management’s Tai Hui points to trade, tariffs, foreign policy and existing regulations, and notes that Democrats would need a two-thirds supermajority to override his veto.
A continued dollar rally would threaten Asian currencies and tighten credit globally, just as governments in the region are contending with the Middle East war and the risk of new US tariffs.
Asia has been here before. The 1997-98 financial crisis had its roots in the Fed’s 1994-95 tightening, when rates doubled in 12 months under Fed Chairman Alan Greenspan. That tipped Mexico into crisis, and the resulting dollar surge then made Asia’s currency pegs impossible to hold.
Thailand devalued first, then Indonesia and South Korea, which together took $118 billion in IMF-led bailouts. Malaysia and the Philippines were pushed to the brink without seeking help. Emerging markets have feared Fed hikes ever since, as the 2013 “taper tantrum” showed.
Now the Iran war has brought the dollar’s wrecking-ball tendencies back. The Indonesian rupiah is down 8.8% this year to record lows, the Philippine peso is down 7.7%, and the Thai baht and Korean won are each down 7%. All of this is happening despite runaway US debt, high inflation, tariffs, tax cuts and heavy spending.
A big part of this story is how Chairman Kevin Warsh’s arrival at Fed headquarters in May isn’t playing out the way Asia hoped. So far, Warsh has run the US central bank notably more hawkish than Trump assumed — at least so far.
He could still be biding his time before doing the president’s bidding. But with US inflation running at 3.7% – a big factor in Trump’s party’s defeat on Tuesday – and the labor market holding up far better than expected, Warsh faces a complicated inheritance.
All of this is making life more challenging for the Bank of Japan. Markets are pricing in Fed tightening by year-end have Tokyo in a whirl. A hawkish Washington will pull capital toward US Treasuries, threatening the Nikkei’s bull run — and the weak yen that juiced corporate profits now leaves Japan exposed to surging import costs and even higher inflation.
Japan is already grappling with stagflation. Growth is tracking at just 0.7% in 2026, while inflation is running about 2%. Given those headwinds, September’s BOJ rate hike to 1%, a 31-year high, may be the last for a long while. A BOJ on hold while the Fed tightens is a near-perfect recipe for renewed yen freefall.
Nobody knows where the Warsh Fed lands six months from now — or how Trump, who tried to fire predecessor Jerome Powell and have him indicted, reacts if his chosen dove fails to deliver rate cuts. But the dollar surging amid a Fed tightening cycle wasn’t on Asia’s 2027 worry list. It is now.
HSBC economist Frederic Neumann argues that monetary officials will remain “on guard in Asia” because “a bouncy US dollar means that there is little reprieve for now.” A surging dollar, he said, makes “everything worse, threatening to suffocate Asian currencies and leaving governments across the region scrambling to sandbag their financial systems.”
The case for caution with dollar optimism, though, is long and growing. Here are seven reasons why dollar optimism may be misplaced.
One, politics. The US political system has not recovered from President Donald Trump’s 2021 attempt to overturn his loss to Joe Biden, and the chaos around this election is likely to cloud policy direction for months.
Two, oil and the Middle East. “For the US dollar, oil remains the most important near-term driver to watch and any outsized move there will more than likely supersede any midterm impact,” said Sarah Ying, head of foreign-exchange strategy at CIBC. “We like positioning for US dollar downside, given that the US administration has taken a more conciliatory tone on Iran in recent days.”
Three, the Fed. Policy may be less aggressive than markets expect. Kevin Warsh, Trump’s latest pick for Fed chair, could argue that lower rates are needed to stabilize the US economy. That would anger the “bond vigilantes” and narrow rate differentials, pushing capital toward Europe, Japan and emerging markets.
Four, growth. US growth will probably lag the rest of the world in 2027, thanks to tighter Fed policy and Trump’s tariffs. That is not a recession call. But with China stabilizing, Europe’s industrial recovery gaining traction, the Bank of Japan slowing its rate hikes and emerging markets holding their own, investors have reasons to rotate elsewhere.
Five, the AI trade. Most recent capital inflows into the US are tied, directly or indirectly, to AI, and the debt taken on by US tech giants has swelled 90% in six months to $3.2 trillion. If returns disappoint and valuations fall, the dollar loses its footing.
Deutsche Bank’s George Saravelos notes that the boom cuts both ways: foreign buying of US stocks now funds the entire US current account deficit, yet roughly 90% of the $20+ trillion in US equities held by foreigners reflects price appreciation, not new buying.
Six, twin deficits. Washington has long gotten a pass, even with the national debt above $40 trillion, thanks to the “exorbitant privilege” of issuing the world’s reserve currency (a phrase coined in the 1960s by French Finance Minister Valéry Giscard d’Estaing).
For now, it’s a confidence game: the US can run large current-account deficits and a deeply negative net international investment position only while global investors keep financing it. If confidence wanes, the dollar could face pressure unseen since the 1970s, and Treasury yields could climb past levels not seen since the early 2000s.
Seven, the wildcards. The dollar could get another leg up if markets turn risk-on, whether because AI-bubble fears prove exaggerated or because Trump winds down the Iran war or eases tariffs.
Japan is the opposite wildcard. After decades of exporting capital in search of yield, Japanese institutions may bring money home as the BOJ shrinks its balance sheet and domestic yields rise.
Standard Chartered’s Steve Englander argues that higher JGB yields make the yen more attractive, and that its low beta, low valuation and restored yield could help it if risk-off conditions come from asset markets rather than oil.
Asia’s Treasury holdings add to the risk. Japan holds nearly $1.1 trillion, China about $620 billion, and the region more than $2.5 trillion in total. Any whiff of Tokyo or Beijing selling could set off panic among other big creditors, including the UK, Canada, the Cayman Islands, Luxembourg and Taiwan.
That helps explain why Treasury Secretary Scott Bessent joined Japan’s Ministry of Finance in buying yen starting in July. Trump called it “friendship.” It looked more like fear: a volatile yen can do damage fast, and so could surging US yields if Finance Minister Satsuki Katayama sold Treasuries to defend the currency. Notably, Bessent funded the purchases with euros, not dollars.
If efforts to weaken the dollar go awry, Team Bessent could end up with higher Treasury yields instead. The dollar’s strength rests on credibility and the belief that US officials won’t play games with its value. Bessent’s recent signals have reopened the question Wall Street hates: is Washington trying to push the dollar lower on purpose?
Asian leaders will have other worries after the midterms, too. Will a bruised Trump White House unleash fresh rounds of tariffs? Might Trump lash out at China for refusing a “grand bargain” trade deal?
Japanese Prime Minister Sanae Takaichi could face pressure to hand over the $550 billion “signing bonus” Trump demanded from Tokyo, and to pay billions a year for hosting US troops in Japan.
Taiwan has fresh reason to fear Trump will use its independence as a bargaining chip in talks with Beijing. And South Korea worries that a lame-duck Trump might invite North Korean leader Kim Jong Un to a summit.
As 2026 winds down, a surging dollar is once again complicating Asia’s development plans for the year ahead. History’s greatest capital magnet risks hoarding the wealth Asia needs to finance deficits, stabilize bond yields and keep equity markets afloat. That no one yet knows what to make of the Warsh era only adds to the unease.
For Asia, the problem is not just that the dollar keeps rising. It’s that the region must prepare for a future in which the world’s most important currency becomes its most destabilizing force.
Follow William Pesek on X at @WilliamPesek