<
article id=”post-952316″>
Asia’s markets reacted to the Democrats’ sweep of Congress as if the region had lost. Over the next year, it’s likely to come out ahead.
The early selling was loud and narrow. South Korea’s benchmark plunged as much as 4% before finishing the day 0.6% higher. Japan’s Nikkei fell around 3%, yet roughly 95 of its 225 members still closed higher, and Taiwan dropped more than 3%
Investors went after anything tied to US data centrer spending. Memory makers, chip equipment suppliers and server builders were dumped, while banks, consumer names and much of the rest of the region were barely touched
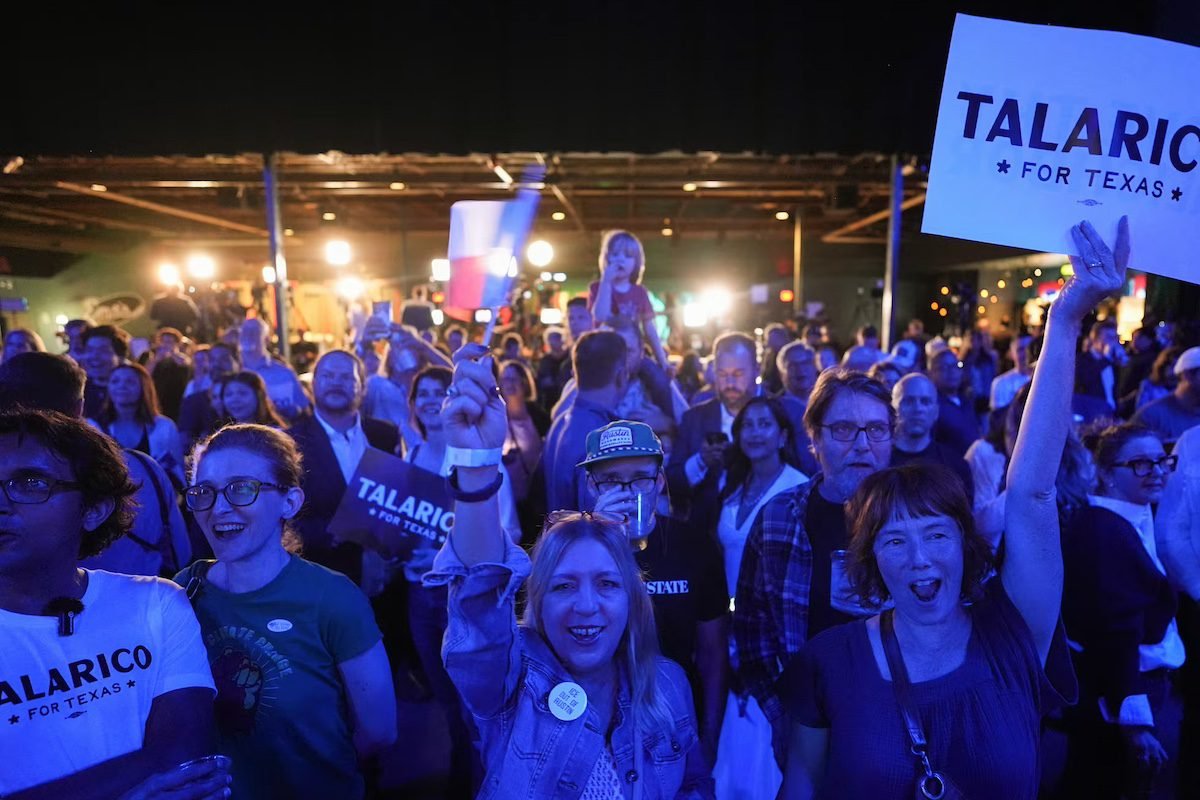
The concern behind that selling is legitimate, even if the panic was overdone. Data centers became a vote-winner for Democrats, with more than half of American voters saying the issue weighed heavily on how they cast their ballot, mostly because of rising power bills.
The new Congress will push developers to carry more of the cost of grid expansion. State governments, many now under fresh Democratic control, have their own levers on permits, water and electricity.
Korea, Taiwan and Japan built their chip industries around supplying those facilities. Orders already placed aren’t going anywhere. The pressure lands on the next wave of projects, on how fast they’re approved and on what they cost.
Demand for high-end chips is likely to grow more slowly, and the companies making them will trade more erratically. A collapse in demand isn’t expected. The world still needs vastly more computing power than it has, and much of it will still be built in America.
Far more important for Asia is what the result does to the dollar and American interest rates.
Democratic control kills any chance of another round of unfunded tax cuts. Bond markets saw it immediately, with the 10-year Treasury yield fell six basis points to around 4.9%, and the dollar slid against major currencies.
I believe both trends will likely run well into 2027, and they amount to a powerful tailwind for the region.
A weaker dollar cuts the cost of servicing dollar debt across Asia. It takes pressure off currencies that have spent much of the past two years defending themselves against a strong greenback.
It also gives Asian central banks something they haven’t had in a long time: room to cut rates to support growth without fearing capital will rush for the exit.
Lower yields in America change the maths for global investors too. When US bonds pay less, emerging market equities and debt look more attractive, and history teaches us that this combination has pulled serious money into Asia.
Japan is the exception, however. A firmer yen squeezes its exporters’ earnings, and its heavy weighting towards chip-related stocks left it more exposed than most on election night.
Oil adds to the relief. Prices fell as the results came in, and Asia imports enormous quantities of crude. Every drop in the price eases inflation and improves trade balances for India, Japan, South Korea and much of Southeast Asia.
A Congress focused on fuel costs at home will want energy prices kept down, and Asia benefits from that pressure without lifting a finger. Sadly, though, tariffs won’t disappear. Most of that power sits with the White House, and Democrats can’t strip it away very easily.
What changes is the friction. Hearings, funding battles, and closer scrutiny of trade deals and investment pledges are coming. Korea, in particular, will be watching whether its investment commitments to the US come under fresh negotiation.
Policy will be slower and messier as a result. For exporters across Asia, slower and messier is easier to plan around than sudden tariff announcements on a Friday evening.
If Democrats force data centers to pay more for power, the companies that make those facilities more efficient stand to gain. Power management, cooling and grid equipment makers across Asia are well placed, and so is China’s clean energy industry, which dominates global supply of solar.
Markets driven by domestic spending look strong too. India and much of Southeast Asia have little direct exposure to American AI spending, but plenty to gain from a weaker dollar, lower oil and easier monetary policy at home.
Asia’s AI champions face a slower order pipeline and more turbulent trading. Almost everything else in the region gains from cheaper money, cheaper energy and a less dominant dollar.
Election night punished Asia’s most famous companies. However, it’s likely that the coming year is likely to reward a much wider set of them, and the region as a whole is better positioned now than it was before America voted on November 3.
Nigel Green is CEO and founder of the deVere Group.