<
article id=”post-952172″>
An old Hindi film from the 1980s shows a politician keeping two speeches in his pocket, one for each way the day might turn. Anyone who has read live commentary on Asia’s largest technology stocks on a popular financial platform this year will recognize the habit.
When a stock opens 8% higher on something that happened elsewhere in the world overnight, out comes the first speech: AI is useful, the spending is durable, the capex cycle has years to run. The available person from the bullish roster is found with a ready statement to corroborate.
When the same stock opens 8% lower the next morning, out comes the second: nobody believes the spending can last, the cycle has peaked, the returns will never arrive. The bear waiting in the wings is given the space to remind us of the TMT times.
On the third morning, whichever speech fits is read again. The loop seems endless. The same desk can read both multiple times in a single week, used as the obvious justification for anything that happens.
Some of the largest companies in the region now earn returns on equity of 40% or 50%. They trade at sub-five times earnings and move as if every day were their results day. A low multiple on exceptional earnings proves no bargain and nobody even bothers about the level, almost yielding to the belief that if the cycle is to reverse, there is no multiple that is too low.
By now, even our likes understand that those who worry about capex slowdown may implicitly assume 80% or more corrections in earnings forecasts, even if we see no logic behind such fears. But doubts about those earnings cannot explain the size and timing of every move that follows.
Somehow no one wants to ask or ponder the obvious questions about who actually trades at the open every day or why so little patient money seems to be left on the other side.
That question is the subject of this piece. We cannot prove all of what follows. Some of it is our highly subjective reading of how these markets now work. A short journey into the gut of markets and discussion of the types of trades will not answer questions.
Our hope is that they generate more discussion than what we have currently, which stands at zero.
The mechanics of desperation
Start with a fact so basic it is easy to forget. On any day, in any stock, every share bought is a share sold. Net flow is always zero. Prices move because one side wants the trade more than the other. A buyer in a hurry lifts the offer and the tick goes up.
A seller in a hurry hits the bid and the tick goes down. The tick measures urgency. Value enters the price only when the people who care about it are present and willing to stand in the way.
Picture a stock that closed at 100. In a market rich in fundamental investors, an overnight seller meets one buyer at 99, a larger one at 97, and someone at 95 who thinks the shares have rarely been cheaper. These buyers disagree with each other about fair value. Their disagreement is what makes them useful, because each lower price brings out another of them.
Now give the same seller a different book. The index fund is waiting for subscriptions. The active fund already holds its maximum weight. The pension fund has no instruction to change anything. The market maker will trade but will not carry a large position into the evening. The investor who believes the business is worth 130 is still reading the news.
The price walks down through empty space, looking for anyone with an order. The auction clears at 92. There are plenty of owners and plenty of activity, with very little demand anywhere near 100. The 92 records where orders happened to meet that morning. By itself, it does not establish that anyone who studies the business believes it lost 8% of its value overnight.
Machines need not even sell much to produce this. They need only sell enough to exhaust the bids queued at the start of the day. Fast liquidity that is cheap and plentiful on quiet days steps back on loud ones, so the queue is shorter than it looks.
When the machines have an event to price in, they can overwhelm whatever stands on the other side. Fundamental investors, who might have refilled the queue, are rarely present in force to provide even a notional resistance in those early hours.
This is why the size of a market says so little about its resilience. Market capitalization is no cash reserve standing behind the bid. This is the only explanation for near-trillion-dollar stocks moving like meme stocks consistently and continuously.
The patient money that owns most of a market can be entirely absent from the minutes in which its price is set. Ninety-nine dollars sit patiently and do nothing. The hundredth dollar, the only one that must trade now, sets the price everyone else reads. Call it the tyranny of the marginal dollar.
A national pension fund that owns 6% or 7% of its home market is a landlord that skips today’s rent auction. When value buyers who respond to price plunges are this scarce, a modest amount of forced selling can move an enormous amount of market value.
World’s after-hours market
These mechanics apply to any stock, anywhere. What is particular to Asia is the bellwether status now granted to a select few stocks in the north of the region.
Consider a large American technology company reporting after the US close. Its own shares trade after hours, but thinly, with wide spreads and little depth. A fund that needs to cut its AI exposure that evening cannot do it there in size without moving the price against itself. So the trade travels. It goes to futures, to options, to baskets, and to the first deep cash market that opens with stocks presumably tied to the same story.
“Presumably” is the critical word. Once a handful of liquid counters become the proxy for global risk-on and risk-off, taking over a role that currency pairs such as the dollar-yen once held, their prices begin to lose touch with their own reality, whether or not the perceived connection is justified. They start to behave like prediction-market contracts on the night’s headlines.
Seoul and Tokyo are the first markets with AI-linked giants to open after the US close, which makes them the natural venue for global traders’ overnight macro trades. Taipei follows an hour later, and Hong Kong soon after. Several other markets in the region open at similar hours, and the antipodean ones even earlier. They are rarely asked to carry the burden of pricing global macro or US tech events.
The burden is heaviest for the largest memory makers listed in Seoul and Tokyo. For a few hours each morning, they are the most convenient place in the world to express a view formed in California the night before. Here is a puzzle we cannot solve, though it shows why “presumably” matters. TSMC sits at the heart of the same AI story. Yet on the same mornings, it often moves a fraction of what the memory makers do.
On the last trading day of October, it fell less than 2% while SK Hynix fell 7%. Perhaps it helps that Taipei opens an hour later, after the first wave has spent itself elsewhere. Perhaps Taiwan’s tighter daily price limit flatters the comparison.
Perhaps it is because of other instruments linked to the stocks or even the track records of their regulators. Perhaps the price-reaction junkies simply find too little excitement in it, now that it is settled wisdom that TSMC lacks the oomph the memory makers offer.
Whatever the reason, the crown for expressing every ship in the Strait of Hormuz and every line from an American earnings call has passed to the memory makers. Nobody can explain why they wear it, or why their valuations obey it.
They do. Commentators, we should admit, see none of this. They have a ready explanation from one of the two rosters discussed at the start of the article for every move these names make, even when similar names elsewhere sit still.
Earnings are only part of it. Statements from the White House tend to land in the American evening. So do many developments in wars, sanctions, oil, and tariffs. A ceasefire rumor, a post about chip export rules, a remark about interest rates: each changes some portfolio’s risk, and each must be expressed somewhere before New York reopens.
Asia has far fewer broad, liquid index and sector instruments than the US. The few counters that are both enormous and responsive get the business because they deliver the most reaction for the money. Macro traders, most of them opinion-agnostic about the companies themselves, have learned this. More of them arrive every year.
A share can serve two purposes. To one investor, it is a claim on a business. To another, it is a handle on a theme, a country, a currency, or a correlation. For these counters, the second purpose increasingly drowns the first. The companies have taken on an extra line of business without asking their boards: supplying trading capacity to people with views about something else.
The correlation then feeds on itself, as each hedge makes the next one look better on a risk model. Some of this has been true for decades. What has changed is the kind of investor on the other side, and how much big-tech news now matters to anyone running global macro money.
Flash boys, slow owners
A dozen years ago, Michael Lewis made the rest of us aware of a race measured in millionths of a second. Asia’s exchanges ran the same race. Tokyo’s new trading system in 2010 handled an order in about ten milliseconds, where the old one took a second or two.
Today it advertises roughly a fifth of a millisecond. Singapore, Hong Kong and the region’s other bourses built co-location halls where trading firms rent racks a few meters from the matching engine.
In the years after the book, this writer sat through more than one exchange presentation on shaving the remaining microseconds. None of it was sinister. Exchanges live on volume, much as brokers do, and the fastest traders bring the most volume. It simply tells us whose needs the plumbing was built around.
Now the sequence, with timings that are only illustrative. At the moment of release, call it zero, the first generation of machines reads the numbers and the words around them. Within a tenth or two of a second, it has decided whether the news is big and which way it cuts.
There is still a contest of interpretations at this stage, but it is settled in a flash, long before any human has finished the first paragraph. In that same flash, the machines also decide which way the global macro books must lean.
What the machines measure the news against deserves more scrutiny than it gets. In a jiffy, they decide whether an announcement cleared the bar. The bar is rarely the published consensus. It is an unofficial expectation for profits, perhaps formed in a few traders’ emails after conversations with a statistically meaningless handful of people.
Increasingly, there are similar bars for margins, capex, and other line items that few outsiders have the tools to estimate with any precision. The market often reacts against convenient, unofficial, and unscientific numbers that nobody hears of until a justification note cites them after the price has moved.
We wrote about these a few weeks ago. We suspect a good deal of ink, and eventually some regulatory attention, will be spent on the unofficial numbers that now rule market reactions.
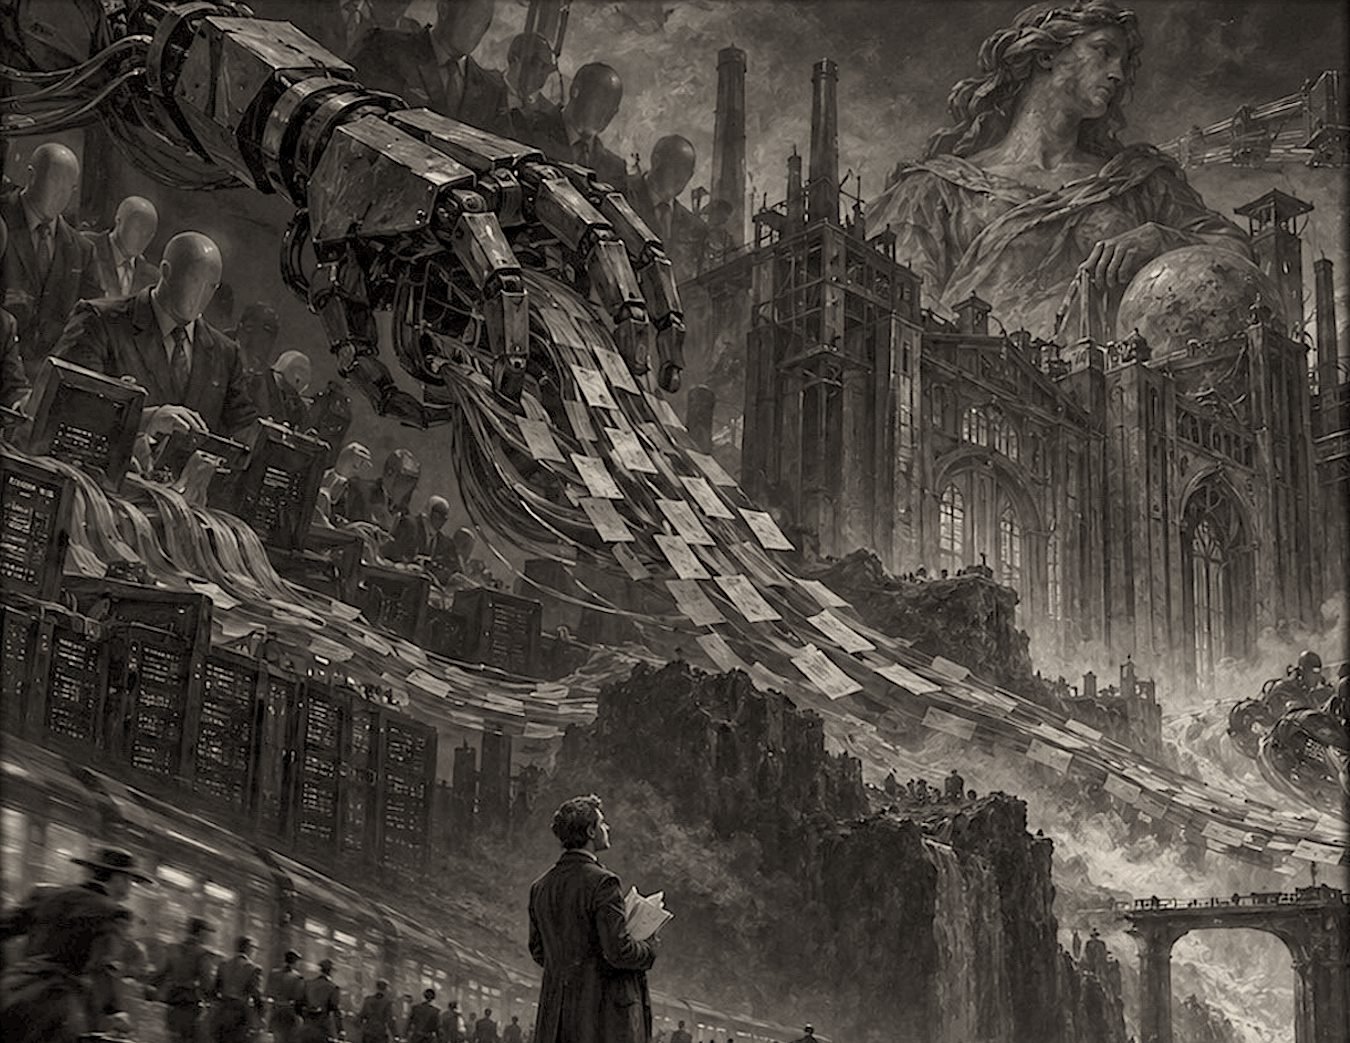
The second generation carries the pricing from that first fraction of a second into the next few minutes, and it carries the bigger force. It needs no judgment of its own. It watches the tape: the first twitch in futures, the lean in correlated stocks, the imbalance in every order book it can see. Once it senses which way the wind is blowing, it hedges, covers shorts, and chases momentum in any market that presumably moves with the story.
In currency markets, where this has been measured, prices jump on the release itself and the heavy volume follows seconds later. The first generation reacts to information. The second reacts to the reaction.
Its flows are strongly autocorrelated: once a direction is set, most of the money leans the same way, because it is watching the same twitch.
Price gaps of mega-caps
By the time Seoul and Tokyo begin pre-market trading, hours later, the decision has long been made. The orders queue, and the opening auction delivers price gaps for mega caps that looked sound the evening before. The servers sit in dark, cooled halls. The local portfolio manager is on the train, scrolling through overnight emails on his phone. He may know the company better than anyone placing those orders.
Knowledge, unfortunately, is not yet an order. By the time he reaches his desk, the auction has priced his portfolio. The argument may still be his. The transaction already belongs to someone else. Speed, in truth, is only part of the story. By the open, he has had hours to read, think, and disagree.
What he often lacks is uncommitted money, room within his mandate, and clients willing to sit through a loss on the first day of being right. Another hour with the announcement would change little. What the open needs is capital ready to meet the orders already waiting.
Retail investors cannot fill the hole. There are millions of them, each with a small account, acting at human speed and usually after the open. A million people who might eventually spot a bargain do not add up to a funded order in the opening auction. Institutional money moves slower still, through committees, risk limits, and orders sliced across days. Where it is plentiful, it eventually leans against the move.
By then, though, the machines have often moved on to price two or three, if not two or three dozen, other headlines, and the committee must start again from a new number. What is nearly absent is a contrarian flow at the moment it matters, while the first movers are setting the reaction.
Much of the initial move therefore persists. Worse, the persistent volatility starts to repel fundamental investors in its own right. Some demand a lower multiple to hold these counters. Others drop them from consideration altogether. The gap holds, the next one stacks on top, and the stock trades week after week like an instrument of global macro.
Every day is results day
A company reports four times a year. Those are its own big information days, when the share price should learn the most about the business. The counters we are describing now trade as if every day were results day, because somewhere in the world it is always somebody’s results day and they are the designated correlated plays.
Watch one theme get replayed. A large US cloud company signals restraint in spending, and its own stock falls hard. That is fair; the news is its own. Its Asian suppliers fall the next morning too, which is plausible enough. A day later, a second giant says something similar. The first company’s stock barely moves because the news belongs to someone else.
If the second giant’s reaction created a material move in the Nasdaq index, the Asian counters will fall again, as if hearing it for the first time. At the end of October, one large US company fell about 7% after hours and closed down little more than 1% the next day. By then, Seoul had already traded the 7%. Asia trades the first draft. New York keeps the revision.
To our biased minds, some of these counters now track big Nasdaq moves, whatever happens to be driving the index. Most large caps listed in the US show far more spine of their own. That loss of specificity and the lack of spine shown by Asian tech majors is why we need to look for the investors who might once have limited it.
Rueing the decline of those with opinions
Before mourning the fundamental investor, it helps to say who he is. He never had to buy and hold. He never had to be a contrarian, a value hunter, or a forensic reader of balance sheets.
Some of the sharpest industry experts this writer has met are momentum investors to the bone. A fundamental investor may happily buy a stock at a hundred times earnings and refuse one at two.
Few things set him apart: he forms opinions. He needs time to form them. His trades follow from an opinion about the security itself. He holds a view on the business, its prospects, and its price, and he puts money behind it. Most of the money in the previous sections needs no such view. We call this group of investors, approximately, opinion-agnostic.
Of course, a typical opinion-agnostic investor also has opinions. But she is working on hundreds of trades. Her primary role is managing risk. She is not beholden to views she may have about any long-term issues.
What she does today is react mostly to today’s events, their impact on her portfolio’s risk characteristics, along with the opportunities she may see in short-term market trends, correlation/relative value arbitrages, and also where she could have a leg up against similar funds on the street and their behaviors that may arrive a fraction later.
Fundamental investor is still around. What he has lost is power. A fund can own a large slice of a company and still not matter at the open, so holdings tables say little. A better gauge is how the people who sell to him treat him now.
When this writer was on the sell side, a three-day marketing trip to Singapore meant eight or nine meetings in ten with investors who argued about valuations, management, and long-term trends. The hedge funds on the schedule argued about the same things; they simply shorted as well as bought. Investors whose main occupation was continuous risk management were rare.
Today, we hear, an analyst on a week-long trip spends eight or nine meetings in ten with fast-money funds and their pods. Long-only managers with tens of billions in the region struggle to get an hour with the best-known analysts. Smaller long-only houses close with dull, depressing regularity while the biggers ones keep cutting the size.
The smallest funds, like GenInnov and those whose AUMs are less than a billion or two, are at the bottom of the pile: some big-name brokers will not send us their research, given the business we can offer. These are impressions, offered as such.
The meetings matter for what they reveal. The investor with an opinion on the business, its trends, and its valuation now has almost no say in how far the price wanders from what he considers fair.
On the mornings that matter, his money is too small, too slow, and too constrained to stand in front of the wave. Event-driven, opinion-agnostic flows set the price at the open. He is not there to meet them, and by the time he arrives, the gap is history. His views may be as good as ever. His weight has become immaterial.
He has even been handed a new job. When a stock falls 10%, he takes the phone call and explains why the fall makes sense. Had it fallen 2%, he would have furnished a smaller room. Had it risen, he would have rearranged the same furniture.
For the counters so cursed, he has no gunpowder left. Standing against the wave means an immediate mark-to-market loss, a nervous risk committee, and clients who read the same headlines. So he stands aside.
Every such investor who waits makes the next gap easier to create. Every easy gap persuades another to wait. When the investor with an opinion cannot hold the line, the obvious candidate is the one with the strongest opinion of all: the company itself.
Impotency of the buyer of last resort
No one knows a business better than the business, and no one has more reason to act when its shares look cheap. This year, the largest memory makers acted. SK Hynix committed about 40 trillion won, roughly $28 billion, to buying and cancelling its own shares over about three months, the first part of at least 60 trillion won planned for the year.
Samsung Electronics bought shares too, for employee share awards. In a single quarter, the two together bought something like a quarter to a third of what every listed company in Japan authorized in its record buyback year.
The tape barely noticed. Foreign investors’ net sales of the two companies’ shares this year came to roughly three times both programs. The stocks ended October about 40% below their June highs, with record profits in hand. Whether the buying softened the fall, no chart can say. It plainly could not hold the line.
Spread over three months, even a vast program comes to a few hundred million dollars a day. A prudent buyer does not stand in front of the opening wave with resting bids. It waits to see where the day begins and buys from there. So the company is largely absent from the very minutes in which its price is set. The buyback arrives daily, like a salary. The selling arrives all at once, like a tide.
Elsewhere, a large company retiring a meaningful slice of its shares at a few times earnings would find plenty of company at the bid: value funds, long-only managers, and opportunists of every kind crowding in behind it. For this handful of counters in Seoul, and to a lesser degree Tokyo, the company buys largely alone.
The scene is familiar from another market. In the 1990s, central banks spent their reserves defending currencies against flows far larger and faster than any intervention, and the Bank of England lost spectacularly in 1992.
Today the defender is a corporate treasurer, the market is equities, and the episode repeats every week. Tens of billions of dollars of buybacks that leave so faint a mark on the price are this decade’s version of an intervention that changes little.
Sadly, nobody in authority appears to find this remarkable. The investors are helpless, the companies are helpless, and the referee seems to be watching another game.
The suspects everyone already knows
It would be unfair to say regulators see nothing. Japan has required high-speed traders to register since 2018 and publishes their activity. The figures show such traders placing about four of every five new orders and nine of every ten cancellations, while accounting for about a third of the value traded.
Korea has registration rules, circuit breakers, and sidecars, and it has spent years policing short sellers. This year it curbed leveraged products after they were blamed for sharp falls. Of all the market-wide circuit breakers Korea has ever triggered, most came this year.
Each of these measures watches a familiar suspect: the short seller, the manipulator, the leveraged retail product, the runaway order. Regulators have an excellent map of the suspects they were already looking for. The question raised here sits off that map.
Who sets the price at the open, and how much patient money stands behind the bid when they do? A regulator could ask what share of opening-auction volume comes from holders of less than a day, how much displayed depth survives the first minute of a shock, and whether its market still has enough long-horizon buyers to absorb a gap. Volatility without wrongdoing appears on no enforcement list.
Markets that kept a little friction seem calmer. Hong Kong’s stamp duty has long discouraged the fastest strategies. Taiwan allows no single-stock leveraged products and limits daily moves to 10%, against 30% in Seoul. We would not make too much of this. Friction has costs, and a price limit can hide volatility as easily as reduce it. The contrast still deserves more discussion than it gets.
Exchanges depend on turnover. So do brokers. Commentators depend on brokers for access and on the daily move for a story. That leaves a reporter with a 10% move and twenty minutes to explain it. He calls a fundamental investor, who obliges: the US company’s capex could mean this, its cash flow could mean that.
Try reversing the day. The same announcement would have supported an equally confident story for a 10% rise, and a 2% move would have produced the same article with a milder adjective. The explanation arrives twenty minutes after the price, wearing a tie. Repeated often enough, the price becomes evidence for the story invented to justify it.
Somebody has to say it, even during the Festival of Lights
We have wished readers a happy Diwali with quirky essays in 2024 and 2025. This year, Halloween’s horror week supplied the fodder.
Still, this may read like a rant at the end of a brutal month, a grievance picked up at a convenient moment. Perhaps it is. Some things, though, did not use to happen. Companies earning returns few businesses have ever matched did not trade at multiples that can be counted on the fingers of one hand while buying back a meaningful slice of their shares, with almost nobody making the margin-of-safety argument and almost nobody buying on it.
Asia’s largest counters did not routinely move 8% or 10% on news from somewhere else, without the anchor one expects of mega caps. Fundamental long-only and long-short investors were not leaving the region year after year, with most of those who stay waiting for the next fall before they act. The sell side did not earn most of its equity trading business from one kind of client.
Maybe this is the ideal structure. When currency traders collided with central banks a generation ago, many people this writer respects argued convincingly that governments should fix their economies and leave market liquidity alone. They may have been right then, and the same advice may be right now.
There was, however, a debate then. Ministers protested, regulators studied leveraged funds, and economists argued in public. Right now, there is barely a conversation. We can understand self-interest-driven brokers and exchanges being quiet, not independent media, the fundamental investor community, or regulators.
The costs are real. When a company’s share price swings by a third on other companies’ news, its cost of capital swings with it. So do decisions about factories worth tens of billions of dollars.
Buybacks that barely register on the price are interventions with little effect. Savers learn that their national champions are among the world’s most volatile instruments, and many leave for good. Little of this looks temporary.
An article like this might find a ready audience in most developed and many emerging markets. Somehow, not in Korea. That is incomprehensible to us, and we will leave it there.
Yet the debate has to begin somewhere. Somebody has to ask what sets these prices before asking, once again, what justifies them. Somebody has to say it. We just did. And with it, we bid you a happy Diwali.