Indonesia has spent a decade trying to turn its mineral wealth into something more valuable than raw commodity exports.
The strategy is ambitious: restrict raw nickel exports, attract investment, build processing capacity and move downstream into electric-vehicle (EV) batteries that will power the next generation of transport and energy storage.
China is central to the ambition. Chinese companies have brought capital, technology, engineering expertise and access to an industrial network that Indonesia lacks. Indonesia, meanwhile, offers something China needs: abundant nickel, a growing market and a strategic production base in Southeast Asia.
In 2024, Indonesia accounted for an estimated 62% of global mined nickel output, making it the world’s largest producer.
The partnership thus joins two countries with very different kinds of economic power, fusing Indonesia’s rich natural resources and China’s dominant industrial ecosystem. But ten years in, questions are rising about whether the partnership will yield genuine industrial upgrading or simply tie Indonesia ever more tightly into China’s industrial orbit.
China’s advantage lies less in producing more batteries than anyone else than in the ecosystem it has spent more than two decades building, in which EVs, batteries, materials, manufacturing, research, finance and infrastructure reinforce one another.
A comparative study of battery policy by the Carnegie Endowment shows how China combined demand creation, industrial policy, manufacturing scale and technological upgrading to establish the world’s most vertically integrated battery industry.
Significantly, Beijing did not begin by simply subsidizing gigafactories. Its early EV programs created demand, while industrial policies pushed manufacturers to improve scale and performance.
A 2015 battery “white list”, for example, tied access to EV incentives to approved battery suppliers and required minimum production and innovation capabilities. The policy favored domestic manufacturers and helped CATL and BYD expand, before the protection was removed in 2019 as Chinese producers grew strong enough to compete without it.
China then added scale, as its battery industry drew demand not only from EVs but increasingly from stationary energy storage. By 2025, EVs accounted for more than half of passenger-car sales in China, while battery storage became another major source of demand.
At the same time, Beijing has begun shifting policy support towards higher-value technologies, including solid-state batteries, even as it tries to reduce low-end overcapacity. This is the ecosystem Indonesia is trying to enter.
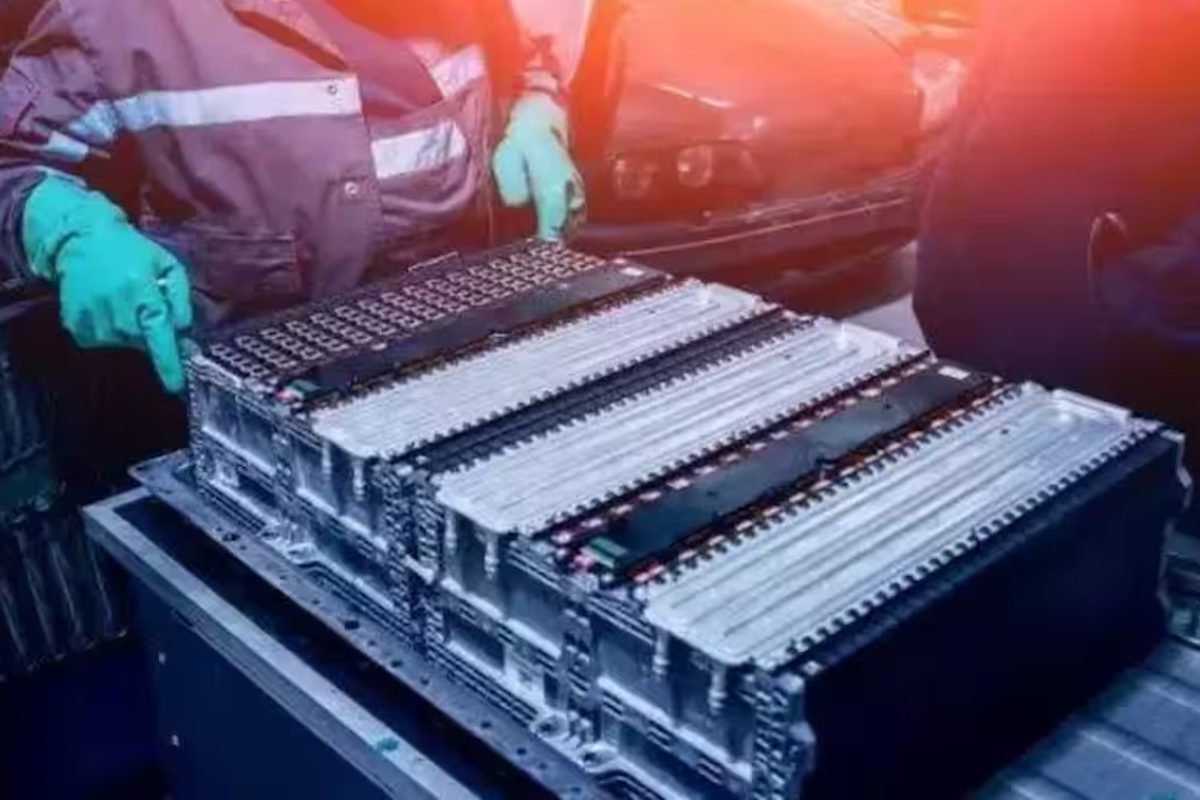
The planned Indonesia Battery Integration Project involving Chinese battery maker CATL’s subsidiary CBL, Indonesia’s state-owned miner Antam and Indonesia Battery Corporation shows the scale of the ambition. The nearly US$6 billion project is designed to span nickel mining and processing, battery materials, cell manufacturing and recycling.
Its first battery plant is expected to have 6.9 GWh of annual capacity, with plans for expansion. For Indonesia, this is a major step beyond exporting raw materials. But it also raises the harder question: who owns the capabilities embedded in this ecosystem?
If Indonesian firms remain dependent on foreign technology, machinery, engineering expertise, intellectual property and management, downstreaming may change where production takes place without fundamentally changing who controls the knowledge behind it.
From Chinese investment to Indonesian capability
This does not mean Chinese investment is a problem. Indonesia probably cannot build a globally competitive battery industry quickly without Chinese capital, technology and industrial partners. The more consequential question is whether Jakarta can turn this dependence into a mechanism for learning.
The relationship is asymmetric but not one-sided. China needs Indonesian nickel and, increasingly, its market and strategic location. Indonesia needs China’s capital, technology and manufacturing ecosystem. The result is a form of asymmetric interdependence, which gives Indonesia room to bargain if that space is leveraged intelligently.
The scale of Chinese involvement is already substantial. The International Energy Agency estimates that Chinese investment in Indonesia’s nickel-refining sector reached about $30 billion in 2024, while Chinese companies accounted for roughly 75% of Indonesia’s refining capacity.
Such concentration brings both opportunity and risk. Chinese firms can bring technologies, suppliers, engineering capabilities and access to global production networks faster than Indonesia could on its own.
But if the most valuable capabilities remain concentrated in Chinese companies, Indonesia could end up with a battery industry that is local in geography but foreign in technological ownership.
Indonesia should therefore look past the amount of foreign capital arriving and ask what it is actually being left behind. Are Indonesian engineers learning to design and improve production lines? Are local suppliers moving into more sophisticated parts and components?
Are universities and companies building serious battery research capabilities? Is intellectual property starting to accumulate at home? And, over time, can Indonesian companies become technology partners rather than remaining suppliers, junior joint-venture partners or providers of raw materials?
These questions may be less visible than the number of factories being built, but they will ultimately determine whether Indonesia is building an industry or simply hosting one.
Indonesia should also avoid locking its strategy into the battery technologies that dominate today. China itself is already looking beyond incumbent chemistries, with increasing attention to solid-state batteries and other next-generation technologies.
If Indonesia builds a sophisticated manufacturing base around today’s technology but lacks the capacity to innovate when the technology changes, it could become trapped in a familiar pattern: moving up the value chain only to find that the frontier has moved again.
The real battery bet
The deeper opportunity, then, lies in using Indonesia’s mineral advantage as bargaining power for technological upgrading, not just in making batteries.
Nickel should be treated as an asset that can win knowledge, skills, research partnerships, supplier development and technology transfer, not just factories. The aim should be to move from resource power to manufacturing power, and, ultimately, technological power.
That requires a broader definition of success. Gigawatt-hours produced matter, but so do the number of Indonesian engineers trained, domestic suppliers upgraded, patents developed, research partnerships created and local firms capable of competing without permanent technological dependence.
Other major battery economies offer key lessons. Japan shows that technological leadership can be lost when commercialization and industrial scale lag behind. Europe shows that regulation, subsidies and ambitious factory plans cannot by themselves guarantee competitive manufacturing.
India shows how difficult it is to create an ecosystem when domestic capacity, supply chains and technology remain fragmented. China’s experience is different because its industrial policy connected demand, manufacturing, firms and technological learning over decades.
Indonesia thus faces a strategic choice. It can become an important production node inside a Chinese-centered battery network, which would still be a considerable economic achievement.
Or it can use that network as a platform for developing capabilities that gradually give Indonesian firms greater technological and commercial autonomy. The first path is easier, but the second is far more valuable.
The Indonesia-China battery relationship should not be viewed through the tired binary of dependence versus independence. Complete autonomy is neither realistic nor necessarily desirable in a globalized industry. The more useful objective is productive interdependence, in which both sides need each other while Indonesia steadily increases the value of what it contributes.
China has already shown that industrial power comes from controlling an ecosystem, not simply producing a product. Indonesia has already shown that resource nationalism can compel global companies to build closer to its minerals. The next challenge is to connect those two achievements without allowing the second to become permanently subordinate to the first.
Indonesia has the nickel and China has the battery ecosystem. The real bet is whether Indonesia can turn its nickel advantage into something China cannot simply supply on its behalf: technological capability and mastery of the industry.
Ronny P Sasmita is senior international affairs analyst at Indonesia Strategic and Economic Action Institution, a Jakarta-based think tank. He holds a PhD from the University of Tokyo.