Economists see stronger human capital, wider workforce integration and productivity gains as central to sustaining long-term growth
Israel’s next finance minister will inherit an economy with a tight labor market, a resilient shekel and a technology sector that continued to operate through nearly three years of war. At the same time, the government will face roughly 350 billion shekels (around $114 billion) in estimated war-related fiscal costs and a public-debt ratio approaching 70% of gross domestic product.
The next government will therefore confront a different economic environment from the one Israel faced before Oct. 7, 2023. The economy has absorbed repeated military shocks without entering a financial crisis, but the fiscal room available to respond to future shocks has narrowed.
Longstanding structural problems also remain unresolved, including weak productivity in parts of the economy, educational gaps and low labor-force participation in some communities.
The Bank of Israel estimates the fiscal cost of the war from 2023 through 2026 at about 350 billion shekels, with roughly half financed through borrowing. By the end of 2025, public debt had risen to 68.5% of GDP from 60.5% at the beginning of 2023, while the government deficit stood at 4.7%.
The central bank separately estimated that the economy produced about 177 billion shekels less between the start of the war and the end of 2025 than it otherwise would have.
Prof. Elise S. Brezis, a macroeconomist at Bar-Ilan University, cautions against treating the rise in debt as Israel’s most urgent economic problem.
“When you look at that compared to many OECD countries, our situation is not so bad,” Brezis told The Media Line.
She pointed to the exchange rate and Israel’s continuing ability to finance itself as indications that markets do not currently view the country as facing an imminent fiscal crisis.
“It is a problem,” she said, “but that’s not the first thing that a new government should take care of.”
Recent Bank of Israel indicators offer some support for that assessment. In September, the bank said Israel’s risk premium was around levels seen before Oct. 7, 2023, while the labor market remained tight.
Economic activity also rebounded sharply during the second quarter of 2026, although the bank cautioned that part of the increase reflected recovery from disruption caused by earlier fighting with Iran.
Adrian Filut, chief economic commentator at the Israeli financial newspaper Calcalist, takes a more cautious view.
Filut told The Media Line that Israel’s next government, regardless of its composition, will enter office with “very little fiscal room.”
In his view, comparisons with heavily indebted large economies can be misleading because Israel faces unusually high geopolitical risk and therefore requires larger fiscal reserves.
Israel is not Switzerland
“Israel is not Switzerland,” Filut said. “You need buffers. You need space and cushions of protection that other governments perhaps do not need.”
For Filut, a debt ratio of about 70% is therefore more consequential for Israel than the headline figure alone might suggest. The country entered the war with fiscal space accumulated over previous years, he said, and has since used much of it.
Defense spending will make rebuilding that fiscal space more difficult.
Before the war, military spending was about 4.5% of GDP. The International Monetary Fund estimated that it reached roughly 8% in 2025 and could remain near 6% in 2026. Even if wartime spending declines, defense would still consume a larger share of the economy than it did before Oct. 7.
The Bank of Israel’s July forecast projected a 2026 deficit of 4.9% of GDP and public debt of about 69%. The projection already incorporated additional defense spending but did not account for every possible increase.
The bank said that adding as much as 25 billion shekels to the defense budget, bringing it to roughly 183 billion shekels, could push the deficit to about 5.5%.
That would leave policymakers with a limited range of options.
“If you can’t touch defense, you don’t have that much room left in civilian and social spending,” Filut said.
The alternatives, he said, include increasing government revenue, broadening the tax base, reducing sectoral spending, cutting other expenditures or borrowing more.
Higher value-added or income taxes would raise substantial revenue but could also weigh on consumption and growth. Filut said he would first examine taxes associated with negative externalities, including pollution and products that generate future public-health costs.
Brezis places greater emphasis on education and human capital.
For her, the more serious long-term risk is whether a growing share of Israelis receives the education needed to participate productively in a modern economy.
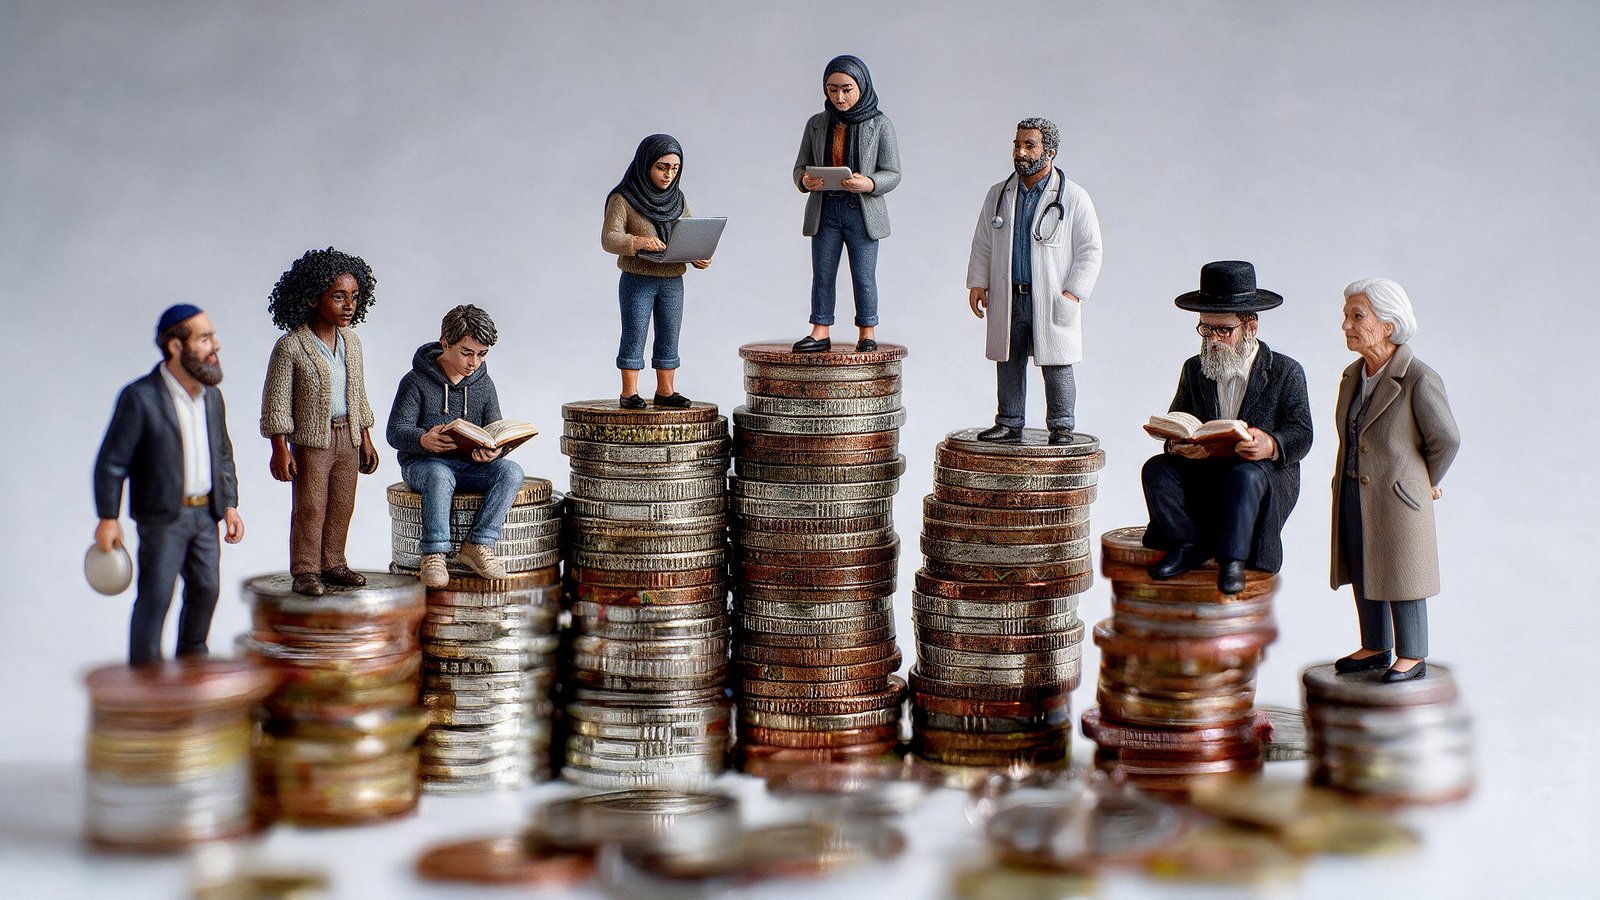
She challenges the common framing of the Haredi economic problem as simply one of workforce participation. Some employment, she said, may not be fully reflected in official statistics. The deeper issue, in her view, is whether workers have the skills needed to enter productive sectors of the economy.
“They don’t know English, they don’t know math,” Brezis said, arguing that publicly funded schools across Israeli society should provide the same core academic curriculum while allowing communities to add religious, cultural or other subjects.
Asked what she would prioritize during the first year of a new government, Brezis proposed ending budget allocations based on family size or sectoral affiliation, redirecting funding toward education reform and beginning a major effort to improve public transportation.
She estimated that changes to sector-based spending could save roughly 20 billion shekels, although that figure was her own estimate.
Filut reaches a similar conclusion on human capital, but from a more restrictive fiscal starting point.
Israel, he said, cannot address its demographic challenge simply by increasing the number of people in employment if many of those jobs remain low-skilled and low-paid.
The game changer is the productive and skilled labor market
“The game changer is the productive and skilled labor market,” he said.
Israel’s economic advantage, Filut argued, rests overwhelmingly on its people rather than natural resources. Maintaining that advantage requires workers who can enter technology, artificial intelligence, cybersecurity and other high-productivity industries.
That makes education and labor-market integration among Haredi and Arab Israelis an immediate economic and budgetary issue rather than one that can be deferred to future governments.
Brezis also sees high tech as the sector capable of sustaining Israel’s relative economic strength.
The locomotive in the 21st-century economy will be high tech
“The locomotive in the 21st-century economy will be high tech,” she said, arguing that Israel’s capacity for entrepreneurship and technological innovation remains intact despite the war.
The two economists differ less on the need for structural reform than on the order in which the next government should act.
Brezis believes Israel has enough underlying economic strength to focus first on education, institutional quality and the allocation of public resources.
Filut wants the next government to begin with a medium-term fiscal plan that puts the debt ratio back on a downward path, followed by education and labor-market reform and measures addressing Israel’s high cost of living.
For Filut, delaying a decision on how to finance permanently higher defense spending could carry substantial long-term costs.
If the money comes from civilian budgets, he said, education, universities, research and public health will face greater pressure. If it comes from additional borrowing, a larger share of future budgets will go toward servicing debt.
Interest is the worst payment
“Interest is the worst payment,” Filut said. “You pay billions of shekels and receive nothing. You are only financing the debt.”